


- The Indian Rupee declines against the US Dollar due to a rise in oil prices over the weekend.
- US President Trump pushes back hopes of near-term diplomacy with Iran.
- Analysts at MUFG expect the RBI to deliver 50bps interest rate hike in the remaining year.
The Indian Rupee (INR) starts the week on a negative note against the US Dollar (USD) due to significant gains in oil prices over the weekend. As of writing, the USD/INR pair is up 0.18% to near 95.99.
At press time, the MCX Crude Oil contract expiring on October 19 is up 4% to near Rs. 9,200.
Currencies from economies, such as India, which rely heavily on oil imports to meet their energy needs, tend to underperform in a high-oil-price environment.
Meanwhile, the Reserve Bank of India (RBI) continues to provide support to the Indian currency through intervention in both spot and Non-Deliverable Forwards (NDFs) markets. "Nearly every day we have seen some amount of interventions, which signals that the RBI wants to keep a firm floor under the rupee for now, traders say, Reuters reported.
What caused a significant increase in oil prices over the weekend?
Oil prices attracted significant bids as United States (US) President Donald Trump pushed back hopes of diplomacy with Iran, adding that additional military strikes before the midterm elections are possible, Fox News reported. Trump expressed confidence that Washington is going to win this war very soon, and as soon as we win it, the oil will go down, way down to what it was before the war.
Meanwhile, Iran’s Foreign Minister, Abbas Araghchi, says his country is open to “real diplomacy” but ready for an “apocalyptic war” if the US attacks again, Al Jazeera reported.
US Yields remain key concern
Elevated US bond yields due to firm expectations that the Federal Reserve (Fed) will hike interest rates again this year continue to remain a key concern for riskier assets. 10-year US Treasury Yields remain firm near its 19-year high of 5.23% posted on Friday.
Strategists at OCBC note that the recent run of resilient US data and sticky inflation has translated into firmer expectations for further Fed action, with “market pricing currently implies around a 70% probability of another 25bp rate hike in October, highlighting the market's growing conviction that the Fed's inflation fight is not yet over.”
RBI caution persists as inflation risks linger despite subdued headline prints
Analysts at Commerzbank highlight that, although "year-to-date CPI inflation has averaged 3.8%, below the Reserve Bank of India's (RBI) FY2026-2027 forecast of 5.0%", the underlying price backdrop remains concerning. They argue that "the persistence of cost pressures suggests policymakers will likely maintain a cautious stance," reinforcing their view that the RBI will stay in "wait-and-see mode." In Commerzbank’s assessment, "higher global crude oil prices and evidence of second-round effects continue to pose upside risks to the inflation outlook," keeping the central bank wary even as headline inflation runs below target projections.
Contrary to the view from Commerzbank, strategists at MUFG view firm domestic growth and signs of broadening in core pressures are strengthening the case for a shallow 50bp hike in second half of FY27, making October’s meeting a live one.
USD/INR Technical Analysis
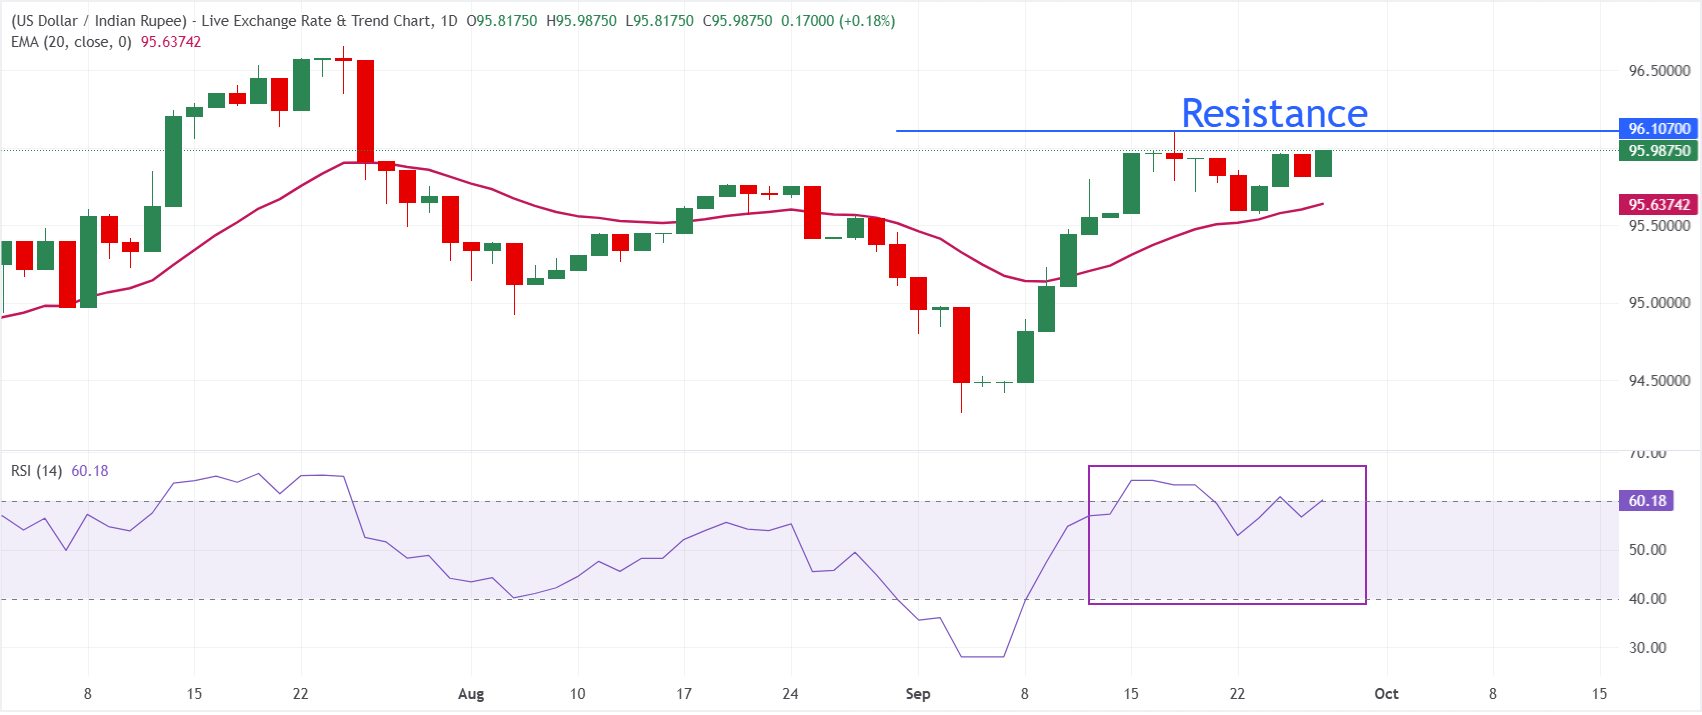
In the daily chart, USD/INR trades at 95.99, holding above the 20-period exponential moving average (EMA) at 95.64, which keeps the near-term bias bullish. The recent recovery from sub-95.00 levels is supported by a Relative Strength Index (RSI) at 60.18, suggesting constructive but not overextended momentum as the pair consolidates near recent highs.
On the downside, immediate support is seen at the 20-day EMA around 95.64, which protects the advance and would need to give way to signal a deeper corrective phase. Looking up, the 96.10 is the immediate hurdle for the pair.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian economy FAQs
The Indian economy has averaged a growth rate of 6.13% between 2006 and 2023, which makes it one of the fastest growing in the world. India’s high growth has attracted a lot of foreign investment. This includes Foreign Direct Investment (FDI) into physical projects and Foreign Indirect Investment (FII) by foreign funds into Indian financial markets. The greater the level of investment, the higher the demand for the Rupee (INR). Fluctuations in Dollar-demand from Indian importers also impact INR.
India has to import a great deal of its Oil and gasoline so the price of Oil can have a direct impact on the Rupee. Oil is mostly traded in US Dollars (USD) on international markets so if the price of Oil rises, aggregate demand for USD increases and Indian importers have to sell more Rupees to meet that demand, which is depreciative for the Rupee.
Inflation has a complex effect on the Rupee. Ultimately it indicates an increase in money supply which reduces the Rupee’s overall value. Yet if it rises above the Reserve Bank of India’s (RBI) 4% target, the RBI will raise interest rates to bring it down by reducing credit. Higher interest rates, especially real rates (the difference between interest rates and inflation) strengthen the Rupee. They make India a more profitable place for international investors to park their money. A fall in inflation can be supportive of the Rupee. At the same time lower interest rates can have a depreciatory effect on the Rupee.
India has run a trade deficit for most of its recent history, indicating its imports outweigh its exports. Since the majority of international trade takes place in US Dollars, there are times – due to seasonal demand or order glut – where the high volume of imports leads to significant US Dollar- demand. During these periods the Rupee can weaken as it is heavily sold to meet the demand for Dollars. When markets experience increased volatility, the demand for US Dollars can also shoot up with a similarly negative effect on the Rupee.


