


- The Indian Rupee gains significantly this week amid weakness in US Dollar, RBIs fresh measures.
- Fed’s Warsh stresses price stability and AI-driven demand.
- The INR’s strength on the back of RBI’s measures could turn out to be short-lived.
The Indian Rupee (INR) gains almost 2% this week against the US Dollar (USD) on the back of weakness in the Greenback and forceful Reserve Bank of India’s (RBI) measures to curb the Greenback's demand.
As of writing on Friday, the USD/INR pair posts a fresh over five-week low at 94.69. In the European session, the US Dollar Index (DXY), which tracks the Greenback’s value against six major currencies, revisits the six-week low near 101.67.
What weakened the US Dollar this week?
Strategists at OCBC highlight that AI-linked investment has become a key support for the US macro and market story, noting that “AI has supported US growth, equities, yields and the USD.” However, they caution that “that strength cuts both ways.” If the investment cycle cools, “those same supports could reverse, leaving the Dollar vulnerable even in a risk-off environment.”
OCBC stresses that “the USD does not always benefit from risk aversion.” When the shock is US-centric, “as with the recent AI financing jitters, pressure on US assets can overwhelm the USD’s traditional safe-haven appeal.” This is significant, they argue, because “AI has become an important pillar of US growth resilience.”
In FX terms, OCBC describes “an unusual combination: risk-off, lower Treasury yields and a softer USD.” They emphasise that “this is not the typical global risk-off shock where investors simply rush into USD.” Instead, “if the source of stress is US-centric, Treasury safe-haven demand can push yields lower even as weaker US asset returns reduce the relative appeal of the USD.”
For now, OCBC views “the latest AI jitters as a bump rather than a break in the broader investment story.” While “concerns look overdone, but they are far from over,” the episode is seen as “a useful reminder for FX.” As they conclude, “the more the USD benefits from AI-driven US growth resilience on the way up, the more exposed it becomes if that support starts to fade.”
The US Dollar extends its weakness on Friday, following remarks from Federal Reserve (Fed) Chair Kevin Warsh at the Fireside Chat with International Monetary Fund (IMF) Managing Director Kristalina Georgieva, in which he stressed achieving price stability, surging investment, and Artificial Intelligence (AI)-led structural growth.
As usual, Fed Chair Warsh has not delivered any meaningful remarks on the monetary policy outlook. Warsh has already stated explicitly that “so-called forward guidance” is not appropriate in the current scenario.
Meanwhile, financial markets remain confident that the Fed will leave interest rates unchanged at the October meeting, but will hike them in December, according to the CME FedWatch tool.
This week, the major trigger for a significant appreciation in the Indian currency remains RBI’s measures to curb the demand for the US Dollar. However, market experts doubt the sustainability of INR’s strength.
RBI steps steady INR, but OCBC warns rebound may prove fleeting
Strategists at OCBC highlight that RBI’s measures of limiting access to certain INR non-deliverable derivatives to hedging purposes, extending the 20% cash reserve requirement to banks’ own qualifying FX hedges, and the special USD window for oil companies are merely a shift in demand for the currency from the spot market rather than a reduction in India’s underlying US Dollar requirements.
OCBC concludes that “we may still see room for some near-term INR gains, but the sustainability of the move will depend on whether portfolio outflows moderate and external pressures from oil prices and US yields ease.” For now, they judge that the latest policy steps “may help establish a firmer near-term footing for INR, rather than mark a decisive reversal in its broader depreciation trend.”
Technical Analysis: USD/INR sees more downside to near 94.30
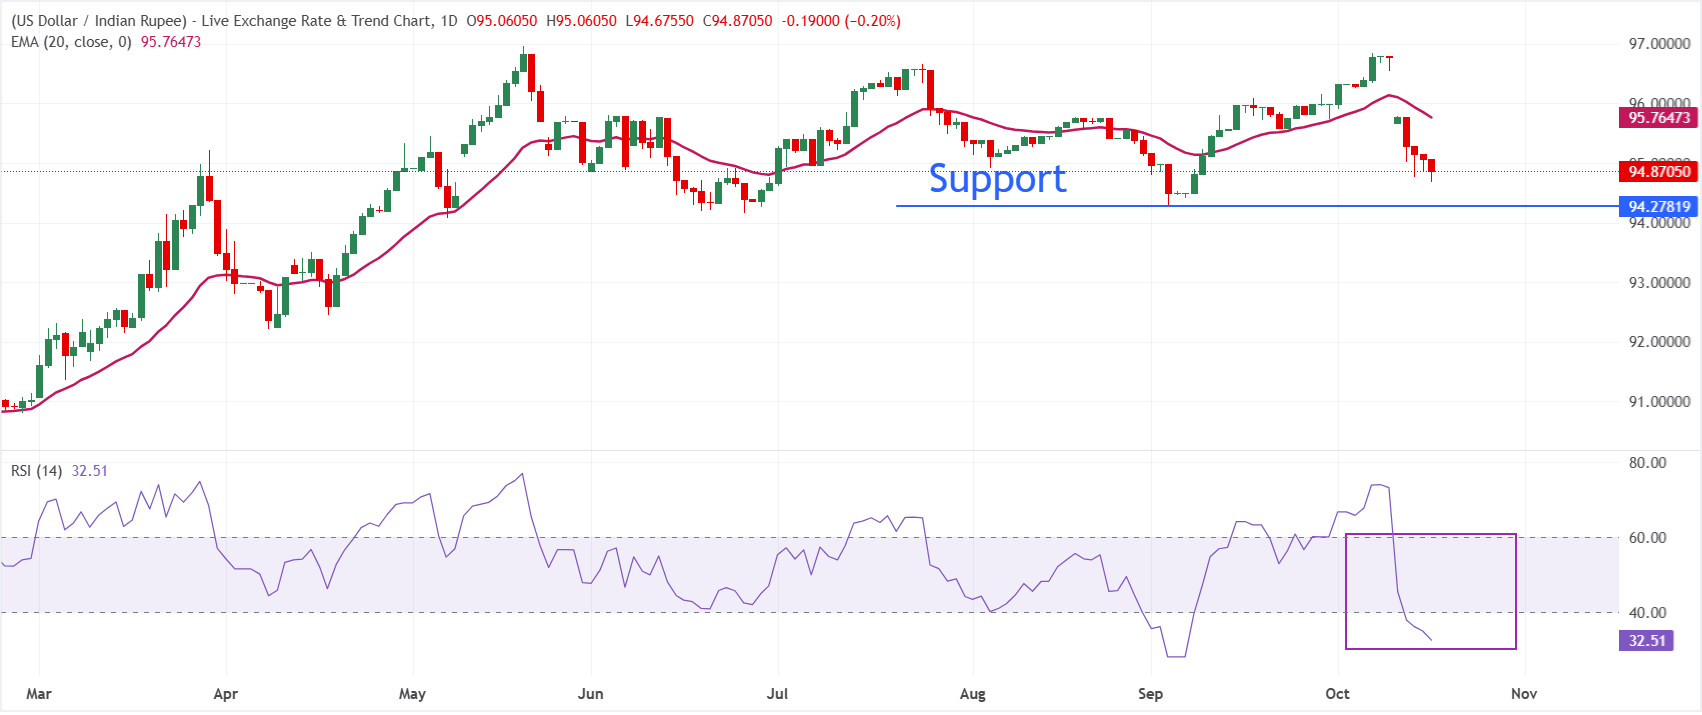
On the daily chart, USD/INR trades below 95.00, keeping a bearish near-term bias as it remains below the 20-period Exponential Moving Average (EMA) at 95.76.
The positioning under this key dynamic barrier suggests the recent slide is still in play, while the Relative Strength Index (RSI) at 32.51 hovers just above oversold territory, hinting that downside momentum is slowing but not yet reversing.
On the topside, immediate resistance is located at the 20-period EMA around 95.76, where any recovery would likely face initial selling pressure. On the downside, the September 3 low at 94.29 is the key support level.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
Indian Rupee FAQs
The Indian Rupee (INR) is one of the most sensitive currencies to external factors. The price of Crude Oil (the country is highly dependent on imported Oil), the value of the US Dollar – most trade is conducted in USD – and the level of foreign investment, are all influential. Direct intervention by the Reserve Bank of India (RBI) in FX markets to keep the exchange rate stable, as well as the level of interest rates set by the RBI, are further major influencing factors on the Rupee.
The Reserve Bank of India (RBI) actively intervenes in forex markets to maintain a stable exchange rate, to help facilitate trade. In addition, the RBI tries to maintain the inflation rate at its 4% target by adjusting interest rates. Higher interest rates usually strengthen the Rupee. This is due to the role of the ‘carry trade’ in which investors borrow in countries with lower interest rates so as to place their money in countries’ offering relatively higher interest rates and profit from the difference.
Macroeconomic factors that influence the value of the Rupee include inflation, interest rates, the economic growth rate (GDP), the balance of trade, and inflows from foreign investment. A higher growth rate can lead to more overseas investment, pushing up demand for the Rupee. A less negative balance of trade will eventually lead to a stronger Rupee. Higher interest rates, especially real rates (interest rates less inflation) are also positive for the Rupee. A risk-on environment can lead to greater inflows of Foreign Direct and Indirect Investment (FDI and FII), which also benefit the Rupee.
Higher inflation, particularly, if it is comparatively higher than India’s peers, is generally negative for the currency as it reflects devaluation through oversupply. Inflation also increases the cost of exports, leading to more Rupees being sold to purchase foreign imports, which is Rupee-negative. At the same time, higher inflation usually leads to the Reserve Bank of India (RBI) raising interest rates and this can be positive for the Rupee, due to increased demand from international investors. The opposite effect is true of lower inflation.






