


Core Snapshot
· 🗳️ Democrats sweep congressional races, easing political uncertainty. Trump says he is ready to work with the Democrats. The Dow surged 1,569.40 points, or 3%, marking its largest one-day advance in a year and a half.
· 🛢️ WTI fell 8.29% to $88.12 per barrel, while Brent dropped 8.67% to $94.62 per barrel.
· 📊 Eurozone October CPI rose 4.0% year-on-year, a three-year high, with energy prices climbing 20.8%. Expectations for an ECB rate hike in December have firmed.
I. Market Outlook
Key Events
- Democrats sweep congressional elections and ease political uncertainty: Following their landslide win, Democrats pledged to check Trump’s agenda, while Trump signalled openness to cooperation. Vance publicly criticised Trump’s Iran policy, arguing the conflict cost Republicans the election. → **The Dow rose 3% to 53,356.12, notching its strongest close in 18 months; the S&P 500 gained 1.6% to 7,688.62; the Nasdaq added 1.4% to 25,736.51.**
- Crude plunges over 8%: WTI fell 8.29% to $88.12/bbl and Brent lost 8.67% to $94.62/bbl. The election outcome and Vance’s criticism of Iran policy triggered a rapid unwinding of geopolitical risk premium. → **The 10-year Treasury yield fell six basis points to 4.89%; gold rose 3.39% to $4,061.1/oz; silver climbed 5.11% to $52.12/oz.**
Exclusive View
A Democratic clean sweep represented the most extreme outcome priced for this election, yet markets rallied hard. The relief from diminished political uncertainty outweighed fears of tighter checks on Trump’s agenda. The Dow’s 3% jump, the sharpest in 18 months, points to rotation away from tech names toward cyclicals that stand to benefit from policy stability. Vance’s public pushback on the Iran war marks the first open split within the Republican Party on the issue and was a major catalyst behind oil’s historic single-day drop. Eurozone CPI hit a three-year peak with energy up 20.8%, cementing bets that the ECB will raise rates in December.
II. Overnight Markets
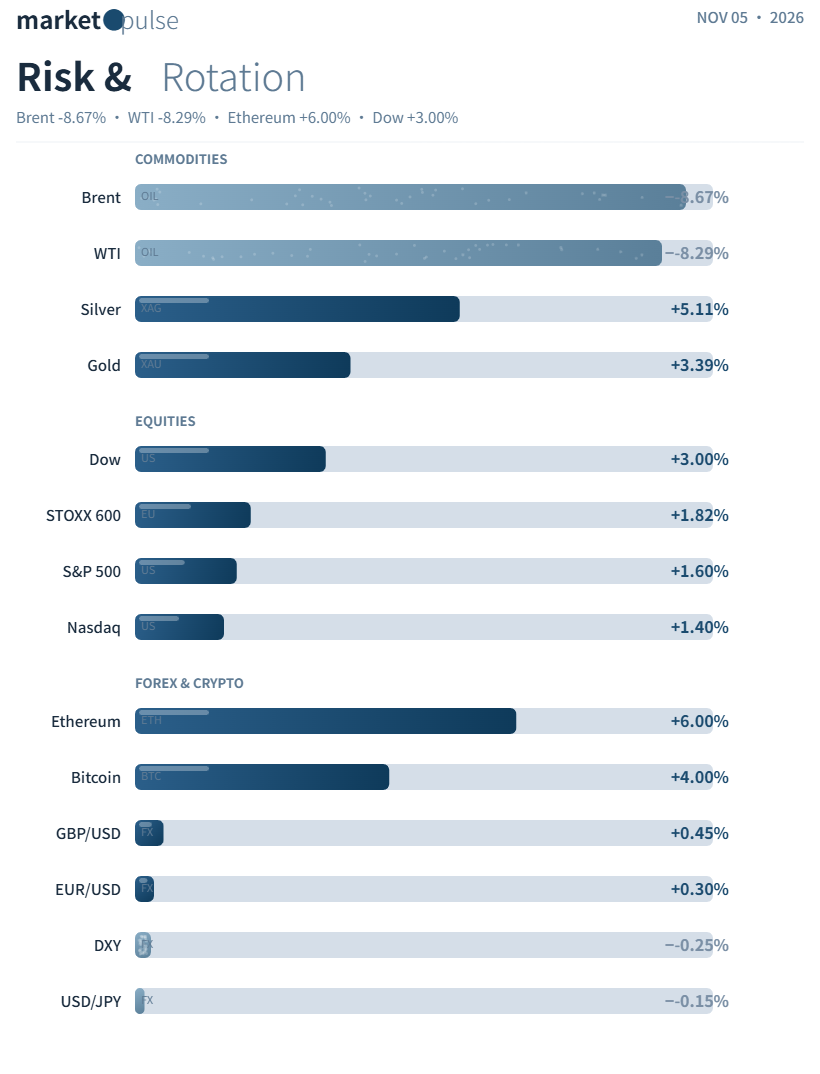
US Equities: The Dow rose 3% to 53,356.12, its largest one-day gain in 18 months; S&P 500 +1.6% at 7,688.62; Nasdaq +1.4% at 25,736.51.
European Equities: STOXX Europe 600 +1.82% at 657.40.
Fixed Income: 10-year Treasury yield -6 bps to 4.89%; 30-year yield -4.5 bps to 5.279%.
Commodities: WTI Dec crude -8.29% at $88.12/bbl; Brent -8.67% at $94.62/bbl. COMEX Gold +3.39% at $4,061.1/oz; Silver +5.11% at $52.12/oz.
FX: DXY fell 0.25% to 101.60, having touched 101.21 earlier, its lowest since September 30. EUR +0.3% at 1.1227; GBP +0.45% at 1.3471; USD/JPY -0.15% at 158.42.
Crypto: Bitcoin rose nearly 4% near $80,800; Ethereum gained more than 6% to $2,440.
III. Macro Headlines
1. 🗳️ Democrats vow to constrain Trump after landslide win; Vance openly criticises Iran strategy. Trump avoided direct commentary on defeat.
Insight: This is the first public rift among Republicans over Iran policy and helped drive crude lower. The removal of near-term policy uncertainty offered support to risk assets.
2. 📊 Eurozone October CPI climbed 4.0% YoY, the highest reading in three years, with energy up 20.8%. Markets are pricing in a higher chance of an ECB December hike.
3. 📉 The US September trade deficit narrowed 0.7% to $105 billion, though surging corporate AI investment kept imports near record highs.
4. 🛢️ EIA data: US crude inventories fell by 865,000 barrels to 409.8 million barrels.
5. 💰 Citi sees gold at $4,500 over zero to three months and $5,000 in the six-to-12-month window.
IV. Corporate News
1. 📱 Qualcomm’s smartphone chip revenue missed estimates in its fourth fiscal quarter. Weak demand and falling Apple-related sales sent shares down more than 4.5% in after-hours trading.
V. Key Releases Today
· 🇬🇧 Bank of England rate decision: Markets broadly expect a 25-basis-point hike.
· 🇪🇺 Eurozone September PPI: Producer-side inflation will draw focus after the hot CPI print.
· 📊 US initial jobless claims for the prior week.
· 🗣️ Speeches from ECB President Lagarde, Cleveland Fed’s Mester and Richmond Fed’s Barkin.





