


Key Snapshot
· 📉 Nasdaq tumbles 694.00 points, or 2.60%, to 26008.86. S&P 500 falls 1.21% to 7663.43, while the Dow edges up 0.02% to 52867.98.
· 🛢️ Brent crude climbs 4.00% to $113.17/bbl, WTI rises 2.39% to $99.47/bbl. Gold drops 2.66% to $4039.8/oz, silver sinks 5.34%.
I. Market Outlook
Exclusive Insight
The 2.60% single-day drop in Nasdaq alongside a sharp pullback in US yields marks a classic risk-asset deleveraging setup. Lower long-end yields are not a bullish signal here; capital is flowing into bonds for safe-haven purposes. Brent’s 4% rally above $113 diverges from gold’s 2.66% selloff. Gold failed to catch a bid amid falling rates, which signals liquidity stress forcing investors to liquidate any tradable asset.
II. Overnight Market Action
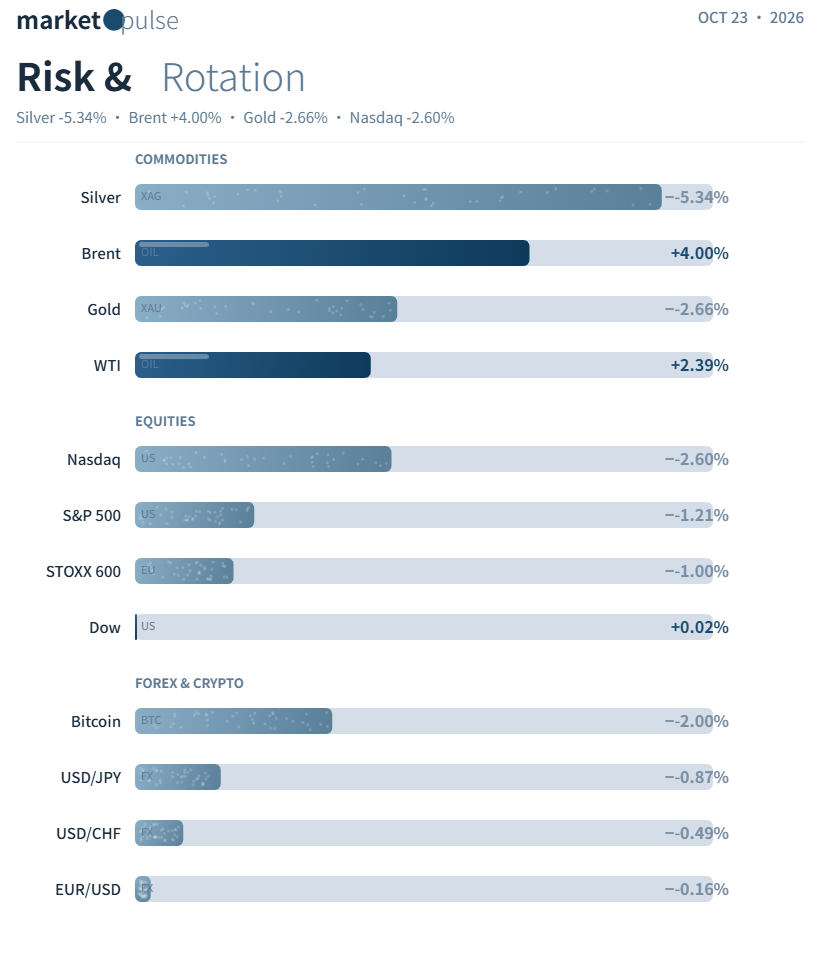
— US Equities: Dow +0.02% at 52867.98; S&P 500 -1.21% at 7663.43; Nasdaq -2.60% at 26008.86.
— European Equities: STOXX Europe 600 falls over 1% to 637.74.
— Bonds: 10-year US Treasury yield -19.3 bps to 4.953%; 30-year yield -15 bps to 5.287%.
— Commodities: Dec WTI crude +2.39% at $99.47/bbl; Brent crude +4.00% at $113.17/bbl. COMEX Gold -2.66% at $4039.8/oz, briefly breaking $4060; Silver -5.34% at $54.63/oz.
— FX: USD/JPY -0.87% at 156.76; USD/CHF -0.49% at 0.8204; EUR -0.16% at 1.1214.
— Crypto: Bitcoin falls more than 2% to around $82,800, pressured in tandem with tech stocks.
III. Macro News
1. ⚠️ Russia-Ukraine conflict escalates amid talk of negotiations. Russia launched a large barrage of ballistic missiles toward Kyiv, while Ukraine sent hundreds of drones targeting Moscow. Following US envoy Witkoff’s visit, both sides signalled talks may resume next month.
Insight: Escalation on the battlefield paired with negotiation rhetoric is a recurring pattern. Each side is seeking a stronger battlefield position ahead of potential negotiations.
2. 📊 US Initial Jobless Claims fell to 194,000, the lowest reading in nearly 57 years. Claims have stayed at or below 200,000 for six straight weeks, underscoring labour market resilience and backing the case for additional Fed hikes.
3. 🛢️ Citi: Oil risks remain skewed to the upside. While crude exports from the Gulf have partially recovered, shipping bottlenecks keep delivered supplies tight.
4. 🇰🇷 Bank of Korea holds rates steady at 3.00% after two consecutive hikes. The governor stressed that a pause does not mark the end of the tightening cycle.
5. 📉 Eurozone October Consumer Confidence fell to -17.9, worse than the -17.0 forecast. European household sentiment continues to deteriorate.
IV. Global Corporate News
1. 🤖 OpenAI is closing in on a financing round of up to $30 billion at a $1.25 trillion valuation, led by Emirati investors. The valuation race among top AI firms intensifies, with Middle Eastern sovereign wealth funds emerging as major AI capital providers.
V. Key Events To Watch
· 🇯🇵 Japan September Nationwide CPI. Imported inflation from a weak yen and high oil prices will be in focus.
· 📊 Flash October PMI prints: Japan manufacturing & services, Germany PMI, US S&P Global manufacturing & services PMI. Synchronised global activity readings will test the real economic impact of Brent’s breakout above $113.






