
Key Snapshots
🛢️ Higher crude prices reignite inflation worries. WTI climbed 3.82% to $103.27/bbl, up 4.29% week-on-week. Brent advanced 3.14% to $116.72/bbl, with a weekly gain of 6.24%. The three main US benchmarks closed lower in unison for the first time this week.
I. Market Outlook
Core Events
Rising crude fuels inflation concerns and weighs on US stocks and Treasuries. WTI settled at $103.27/bbl (+3.82%), Brent at $116.72/bbl (+3.14%), marking weekly rises of 4.29% and 6.24% respectively. The Dow fell 1.23% to 52215.16, S&P 500 dropped 0.52% to 7623.68, Nasdaq slipped 0.21% to 25955.34. The 10-year US Treasury yield rose 3.5 bps to 4.988%.
Trump signaled a potential new military strike against Iran. At a rally in Florida, he said “we may do another small Operation Epic Fury”. Zelensky stated negotiators from Ukraine, Russia and the US will meet in Abu Dhabi in early November. Geopolitical risk and diplomatic signals sit side by side, keeping oil prices anchored at elevated levels.
Exclusive Viewpoint
The four-year high in corporate selling-price inflation deserves more attention than the softening composite PMI. Slower growth paired with rising pricing power suggests inflation may prove stickier than priced in. Trump’s remarks on Operation Epic Fury put conflict risk back into focus. Apple’s first foldable iPhone reports screen cracking issues, a major quality test for the landmark product under new CEO Ternus.
II. Overnight Market Action
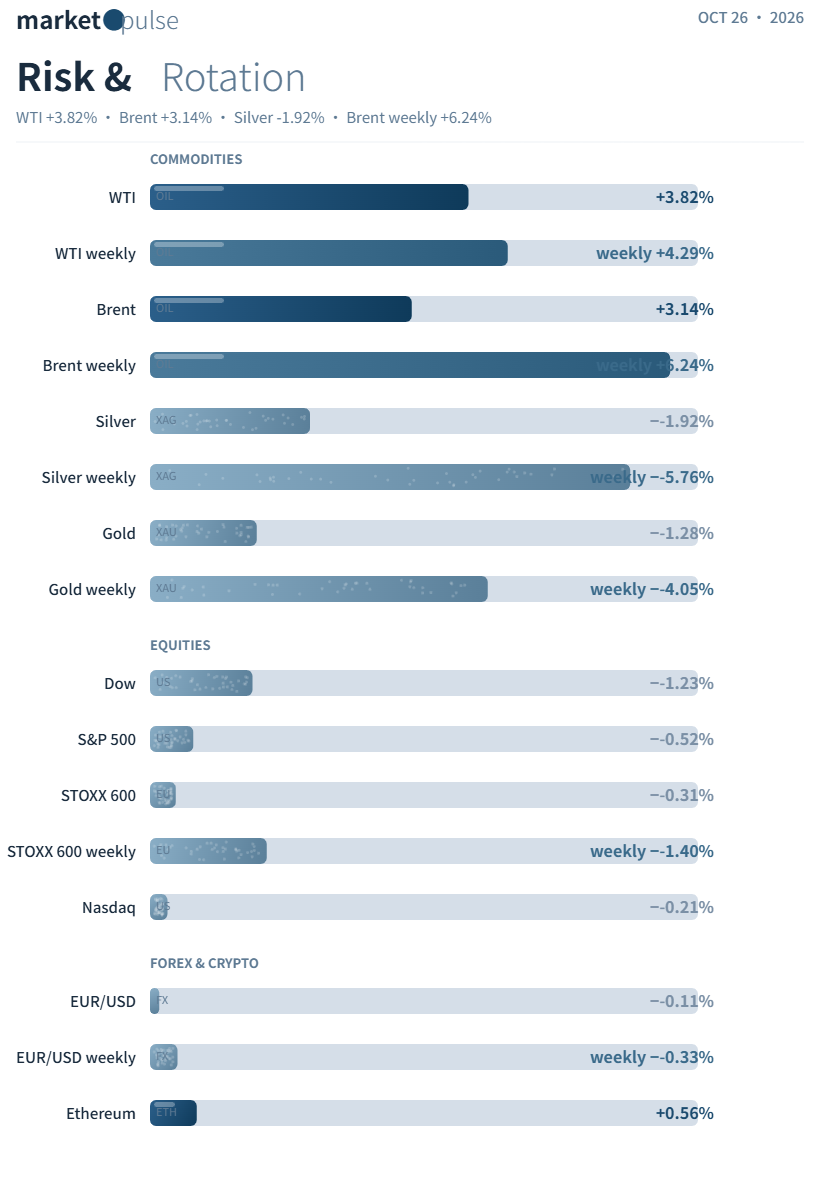
US Equities: Dow -1.23% at 52215.16; S&P 500 -0.52% at 7623.68; Nasdaq -0.21% at 25955.34.
European Equities: STOXX Europe 600 -0.31% at 635.77, down roughly 1.4% for the week.
Rates: 10-year US Treasury yield +3.5 bps to 4.988%, down 11 bps on the week for the third consecutive weekly decline.
Commodities: WTI Dec crude +3.82% at $103.27/bbl, weekly +4.29%. Brent +3.14% at $116.72/bbl, weekly +6.24%. COMEX Gold -1.28% at $3991.1/oz, weekly -4.05%. Silver -1.92% at $53.711/oz, weekly -5.76%.
FX: US Dollar Index little changed week-on-week. Euro -0.11% to 1.1202, down 0.33% for the week.
Crypto: Bitcoin slightly lower at $81234.67; Ethereum +0.56% at $2395.73.
III. Macro Headlines
1. 🛢️ Trump hints at possible fresh military action against Iran. He told supporters in Florida the US could launch another limited Operation Epic Fury. Zelensky confirmed Ukrainian, Russian and US negotiators will gather in Abu Dhabi early November.
Insight: Markets are pricing in elevated conflict risk alongside tentative diplomatic channels. Trump’s rhetoric normalises the threat of strikes, forcing traders to reassess upside risk for oil.
2. 📊 US October composite PMI eases to 57.6, yet corporate selling prices hit a four-year high. Slower activity alongside stronger pricing power keeps inflation pressures simmering. French PMI prints all fell below the 50 expansion threshold.
Insight: Surging selling prices signal sticky inflation, a bigger red flag than the PMI pullback.
3. 📉 Hundreds of thousands protest across France; unions have called for further demonstrations and a major strike in one week’s time. Social stability risks in Europe remain on the radar.
IV. Corporate News
1. 📱 Apple’s debut foldable iPhone hits trouble, with screen cracking reports emerging across global markets. Some users reported failures after fewer than 20 folds, creating a critical quality challenge for the flagship innovation under CEO Ternus.
2. ☁️ Amazon AWS capacity is fully booked through next year, with most 2028 slots already reserved. The CEO said AI annualised revenue tops $25 billion, growing hundreds of times faster than AWS in its early days, even with $220 billion in committed investment. The AI infrastructure supply gap remains wide.
3. 📡 SpaceX is in talks to connect to 80,000 cell towers, targeting status as America’s fourth-largest wireless carrier. Major US telecom stocks fell on the news as SpaceX expands from aerospace into mass communications.
V. Key Events To Watch
🇧🇷 Brazil’s presidential runoff voting kicks off on the 25th, with results expected on the 26th. The political direction of Latin America’s largest economy carries direct implications for commodities and emerging-market assets.