


Core Snapshot
· 🕊️ Trump ruled out strikes on Iran after midterms and signalled a potential deal, lifting diplomatic hopes and sending oil sharply lower. WTI fell 7.36% to $96.46/bbl, Brent dropped 7.63% to $104.77/bbl.
· 🗳️ Americans head to the polls for midterm elections today, voting for both chambers of Congress and 36 state governorships. A record 50 million ballots were cast early as of Oct 31.
I. Market Outlook
Key Events
- Crude crumbles as US-Iran diplomacy gains traction: Trump said he would not pursue military action against Iran post-election and left the door open for an agreement. The shift triggered a sharp unwinding of geopolitical premium. WTI fell 7.36% to $96.46/bbl; Brent lost 7.63% to $104.77/bbl. The 10-year Treasury yield eased 3.3 bps to 4.896%.
Exclusive View
The 7%+ single-day slide in oil marks a rapid unwinding of geopolitical risk premium. Trump’s explicit rejection of post-midterm strikes directly reverses market pricing for prolonged conflict. Election results, however, will shape his policy flexibility toward Iran, keeping crude volatility elevated until the outcome is clear. Apple’s beat reinforces resilient demand and pricing power for the iPhone 18 Pro, a standout result amid rising memory chip costs.
II. Overnight Markets
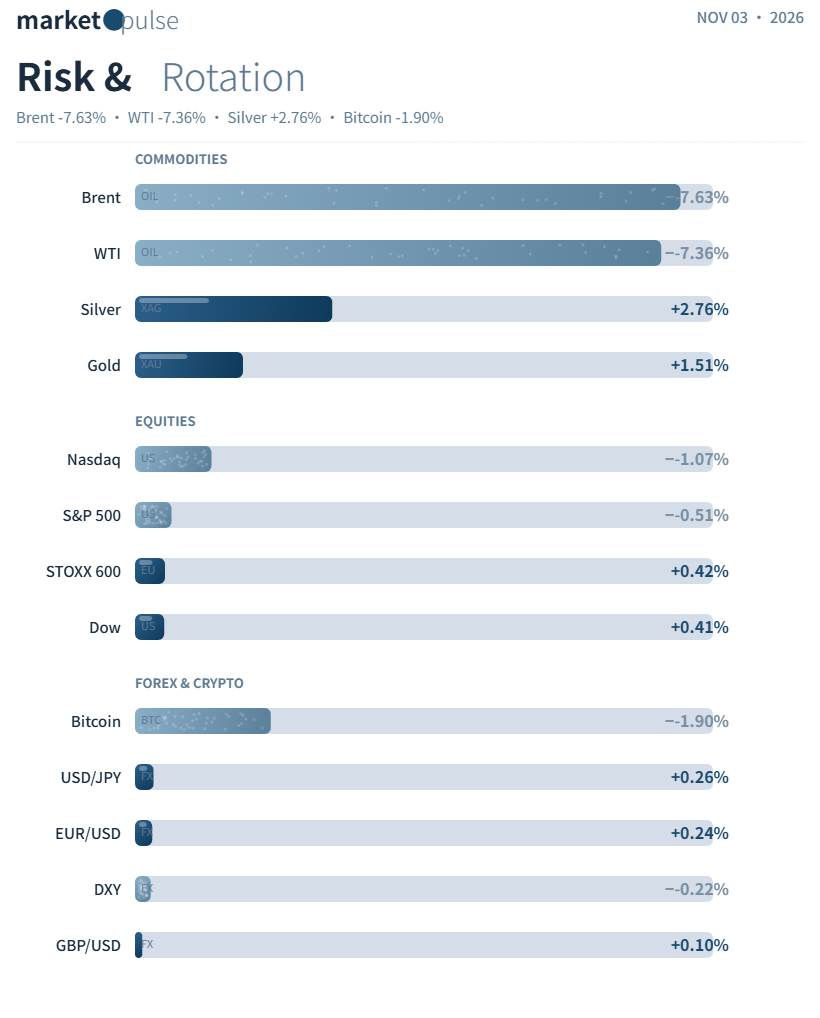
US Equities: S&P 500 -0.51% at 7541.40; Nasdaq -1.07% at 25164.32; Dow +0.41% at 51983.98.
European Equities: STOXX Europe 600 +0.42% at 649.44.
Fixed Income: 10-year US Treasury yield -3.3 bps at 4.896%; 30-year -3.8 bps to 5.271%; 2-year flat at 4.581%.
Commodities: WTI Dec crude -7.36% at $96.46/bbl; Brent -7.63% at $104.77/bbl. COMEX Gold +1.51% at $3957.67/oz; Silver +2.76% at $50.64/oz.
FX: DXY -0.22% to 101.76; EUR +0.24% at 1.1185; GBP +0.10% at 1.3405; USD/JPY +0.26% at 157.94.
Crypto: Bitcoin slipped 1.9% to near $76,700, tracking weaker tech shares.
III. Macro Headlines
1. 🕊️ Trump rules out post-midterm strikes on Iran, flags scope for negotiated deal. Diplomatic optimism drove WTI’s 7.36% rout.
Insight: Geopolitical premium is being priced out rapidly. Election results will constrain or expand Trump’s policy options, so oil volatility stays high.
2. 🗳️ US midterm voting kicks off today; 50 million early votes set a new record by Oct 31. Trump’s approval ratings remain near historic lows, with many voters framing the ballot as a referendum on the Republican agenda.
Insight: The outcome will directly shape his Iran posture and domestic fiscal priorities, making it the week’s biggest political catalyst.
3. 📊 US October manufacturing PMI rose to 55.5, with input prices at 75.2. Factory inflation stays elevated on strong domestic demand.
4. 🇪🇺 Eurozone October final manufacturing PMI printed 52.7, slightly above flash estimates. Growth remains solid though momentum moderates.
IV. Corporate News
1. 📱 Apple topped estimates with Q4 revenue of $114.48bn and EPS of $2.10. Strong take-up and pricing power for iPhone 18 Pro offset climbing memory chip expenses.
2. 🤖 Anthropic updated its IPO prospectus, highlighting mounting profitability pressure. Q3 revenue hit nearly $17bn, up 11x YoY, while net loss widened 92%. The firm has pledged roughly $900bn in compute commitments, extending the high-growth, heavy-loss model.
V. Key Releases Today
· 🗳️ US Midterm Elections: votes for Congress and 36 state governors; results will steer Iran policy and risk appetite.
· 🇦🇺 RBA rate decision and monetary policy statement. Markets have priced in a possible 25bp hike.
· 📊 US September JOLTS job openings and factory orders.
· 🇯🇵 Japanese markets closed for Culture Day holiday.





