


Bank of Japan (BoJ) Governor Kazuo Ueda is addressing the press conference, explaining the reason behind raising the key interest rate by 25 basis points (bps) to 1.25% from 1.00% at the September meeting.
BoJ press conference key highlights
Japan's economy recovering moderately albeit with some weakness.
Japan's economy likely continue growing moderately.
Must pay attention to impact of Middle East situation, AI-related demand expansion and FX on Japan's economic activity, prices.
Japan's financial conditions have been accommodative.
There is risk of underlying inflation overshooting 2% price target given firms' wage, price setting behavior becoming more aggressive, mid- and long-term inflation expectations rising.
To keep raising rate in response to economy, prices.
Middle East situation continues to be uncertain.
Stage for policy conduct has changed.
Short-term objective has changed significantly.
No comment about short-term market moves.
We want to see whether trend inflation stays at 2% after reaching it around end of FY2026 into FY2027.
Rate hikes have gradually tightened financial conditions.
Not mulling board member change next year for policy.
BoJ flags risk of inflation overshoot, keeps door open for further Yen-supportive hikes
FXS Speechtracker shows the BoJ press conference score at 8.2, exactly in line with the speaker’s historic average, signaling a consistent tone but with a clear hawkish tilt versus earlier “transitory” narratives. The emphasis on Japan’s economy “recovering moderately” and the risk of underlying inflation overshooting the 2% target, amid more aggressive wage and price setting and rising inflation expectations, reinforces a bias toward continued rate hikes that should be supportive for the Yen.
The BoJ highlighted that the “stage for policy conduct has changed” and that the short-term objective has “changed significantly,” underscoring a shift away from ultra-accommodative settings even as financial conditions remain broadly easy. By stressing the intention “to keep raising rate in response to economy, prices” while watching Middle East risks, AI-related demand, and FX effects, the remark confirms a cautious but ongoing normalization path that markets can interpret as mildly Yen-positive, especially if trend inflation stays near 2% into FY2026–FY2027.
The section below was published on September 18 at 2:50 GMT to cover the Bank of Japan's monetary policy announcements and the initial market reaction.
The Bank of Japan (BoJ) board members decided to raise the short-term interest rate by 25 basis points (bps) to 1.25% from 1.00%, following the conclusion of its two-day monetary policy review meeting on Friday.
The decision aligned with the market expectations.
Summary of the BoJ’s Monetary Policy Statement
BoJ makes rate policy decision by 7-2 vote.
BoJ board members Asada, Sato dissented to decision on rates.
Underlying inflation approaching 2%.
Financial conditions are accommodative.
Will continue to raise interest rates in response to economic and price developments as well as financial conditions.
Will consider timing, pace of rate hikes while examining likelihood of realising baseline scenario and risks.
Will scrutinise impact of Middle East developments, AI demand and FX on economy, prices, in setting policy.
Will conduct monetary policy as appropriate from perspective of sustainably, stably achieving inflation target.
Accommodative financial environment will be sustained after policy rate change, thereby supporting economic activity.
It is becoming important to stabilise underlying inflation around 2%.
Japan's economy recovering moderately.
Financial conditions are accommodative.
Inflation expectations are heightening moderately.
Japan's economy to continue growing moderately.
Necessary to pay attention to impact of Middle East situation on financial, forex markets, economy, prices.
Underlying inflation likely to gradually accelerate, reach level consistent with 2% target from latter half of fiscal 2026 through fiscal 2027.
Necessary to pay attention to effects of global ai-related demand, forex on Japan's economy, prices.
Must avoid underlying inflation from overshooting 2% target.
Wholesale inflation remains elevated due to impact of oil, FX, AI-demand.
Price pressures in B-to-B trade spreading to consumer prices.
Firms continue to pass on cost from rising wages.
Inflation expectations continue to heighten, underlying inflation approaching 2%.
Economy, prices moving in line with baseline projection of our outlook report.
Must be vigilant to risks, particularly Middle East developments, AI demand, FX volatility and their impact on economy, prices.
CPI has been moderately rising recently, being in the range of 1.5-2.0%.
Effects of a rise in import prices have been emerging, with moves to pass on wage increases to selling prices continuing.
Recent depreciation of the yen likely to lead to an increase in prices.
There is risk underlying inflation could overshoot 2% target.
Udged that it was necessary to adjust degree of monetary support from perspective of sustainably, stably acheiving price target.
BoJ flags inflation risks as yen weakness and ai demand fuel rate-hike bias
The 8.2/10 FXS Speechtracker score is exactly in line with the speaker’s historic average, but the emphasis on underlying inflation approaching 2% and the risk of overshooting marks a clear hawkish tilt. Repeated references to accommodative financial conditions alongside a commitment to continue raising interest rates as the economy recovers moderately signal a gradual normalization bias that supports a stronger YEN narrative.
The focus on Middle East developments, AI-related demand and recent YEN depreciation feeding into wholesale and consumer prices reinforces upside inflation risks and justifies adjusting the degree of monetary support. By stressing the need to stabilise inflation around 2% while keeping conditions accommodative, the statement underpins a controlled but persistent tightening path that is likely to be interpreted as mildly YEN-supportive over the medium term.
Market reaction to the BoJ policy announcements
The Japanese Yen (JPY) attracts some sellers following the Bank of Japan’s rate hike decision. At the press time, the USD/JPY pair is up 0.49% on the day to trade at 156.73.
Japanese Yen Price Last 7 Days
The table below shows the percentage change of Japanese Yen (JPY) against listed major currencies last 7 days. Japanese Yen was the weakest against the US Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | 1.12% | 1.05% | 1.60% | 1.19% | 0.42% | 1.24% | 1.43% | |
| EUR | -1.12% | -0.07% | 0.43% | 0.03% | -0.71% | 0.11% | 0.30% | |
| GBP | -1.05% | 0.07% | 0.50% | 0.12% | -0.61% | 0.21% | 0.38% | |
| JPY | -1.60% | -0.43% | -0.50% | -0.39% | -1.14% | -0.31% | -0.24% | |
| CAD | -1.19% | -0.03% | -0.12% | 0.39% | -0.75% | 0.08% | 0.23% | |
| AUD | -0.42% | 0.71% | 0.61% | 1.14% | 0.75% | 0.82% | 1.03% | |
| NZD | -1.24% | -0.11% | -0.21% | 0.31% | -0.08% | -0.82% | 0.18% | |
| CHF | -1.43% | -0.30% | -0.38% | 0.24% | -0.23% | -1.03% | -0.18% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Japanese Yen from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent JPY (base)/USD (quote).
This section below was published on September 17 at 22:00 GMT as a preview of the Bank of Japan Interest Rate Decision.
- The Bank of Japan is set to hike interest rates to 1.25%, the highest level in 31 years.
- Higher inflation, strong GDP data and pressure from the US administration are pushing the BoJ to step up its tightening pace.
- The US Dollar has pared some losses this week, fuelled by the Fed’s hawkish monetary policy stance.
The Bank of Japan’s (BoJ) monetary policy meeting will close a week packed with central bank decisions on Friday, with markets particularly interested in confirming expectations of a hawkish shift that has boosted a strong Japanese Yen (JPY) recovery in September.
Futures markets are practically fully pricing a quarter-point rate hike this time, which would push the BoJ’s benchmark interest rate to its highest level in about 31 years, amid higher inflation, rising wages, and pressure from US Treasury Secretary Scott Bessent.
The Japanese central bank will follow the Federal Reserve (Fed) and the European Central Bank (ECB) in tightening monetary policy as the war in the Middle East fuels global inflation. The Strait of Hormuz remains practically closed, and recent developments threaten the Red Sea alternative route, pushing Brent Oil prices above $100 and spurring serious concerns about supply disruptions.
What to expect from the BoJ interest rate decision?
Barring a highly unlikely surprise, the Bank of Japan will raise its benchmark interest rate from 1% to 1.25% on Friday, drawing monetary policy closer to levels the bank considers neutral for the Japanese economy. The decision is likely to obtain the support of the broad majority of the Policy Board, with recently appointed committee member Toichiro Asada likely to dissent, as he did at June’s meeting.
Rising inflationary pressures, among other reasons, have prompted the BoJ to accelerate its monetary tightening pace. So far, the bank has kept a semi-annual hiking pace, while September’s rate increase, if confirmed, would follow a previous one in June. Markets have speculated on a half-point rate hike, but considering the cautious approach to monetary policy of the Japanese central bank, that option seems out of the question.
Japan’s Consumer Price Index (CPI) data from July revealed that prices grew at their fastest pace in the last seven months, reaching 1.9%, just below the BoJ’s 2% target for price stability. Beyond that, wages have continued rising, which hints at stronger price pressures in the near-term, altogether heightening the risk that the central bank might fall behind the inflation curve if it sticks to the gradual tightening path seen hitherto.
Japan’s broader economic outlook remains supportive too. The Gross Domestic Product (GDP) beat expectations in the second quarter, with a 1.4% annualised growth, providing fairly favourable conditions for some monetary tightening.
Against this backdrop, investors are waiting for the bank to deliver a clear message outlining a firmer monetary policy normalisation cycle ahead. This would come after less-than-subtle pressures from the US administration, following an exceptional coordinated intervention between the US and Japan in Forex markets that halted a long-lasting Yen decline in late July.
Analysts at ING, however, warn that the market might be overestimating BoJ’s hawkishness, arguing that Japan’s “aggressive pro-growth strategy” will act as a brake on any rapid shift to tighter policy by the BoJ. They note that the government “will no doubt express its views against a more aggressive tightening cycle,” adding that it is “hard to see government officials backing a much faster tightening cycle of either a 50bp hike in September or back-to-back hikes in September and October.”
How could the Bank of Japan's monetary policy decision affect USD/JPY?
USD/JPY is showing a 2.5% decline in September so far, as a series of hawkish comments by BoJ officials has prompted traders to ramp up bets on a steeper BoJ tightening cycle. This has triggered a massive short covering in Japanese Yen, with large speculators flipping their net positioning to long JPY for the first time since February.
The US Dollar (USD) has managed to regain some ground this week. The Federal Reserve (Fed) provided a fresh boost to the Greenback on Wednesday by hiking interest rates and pointing to further tightening in coming months, but the broader near-term bias remains bearish.
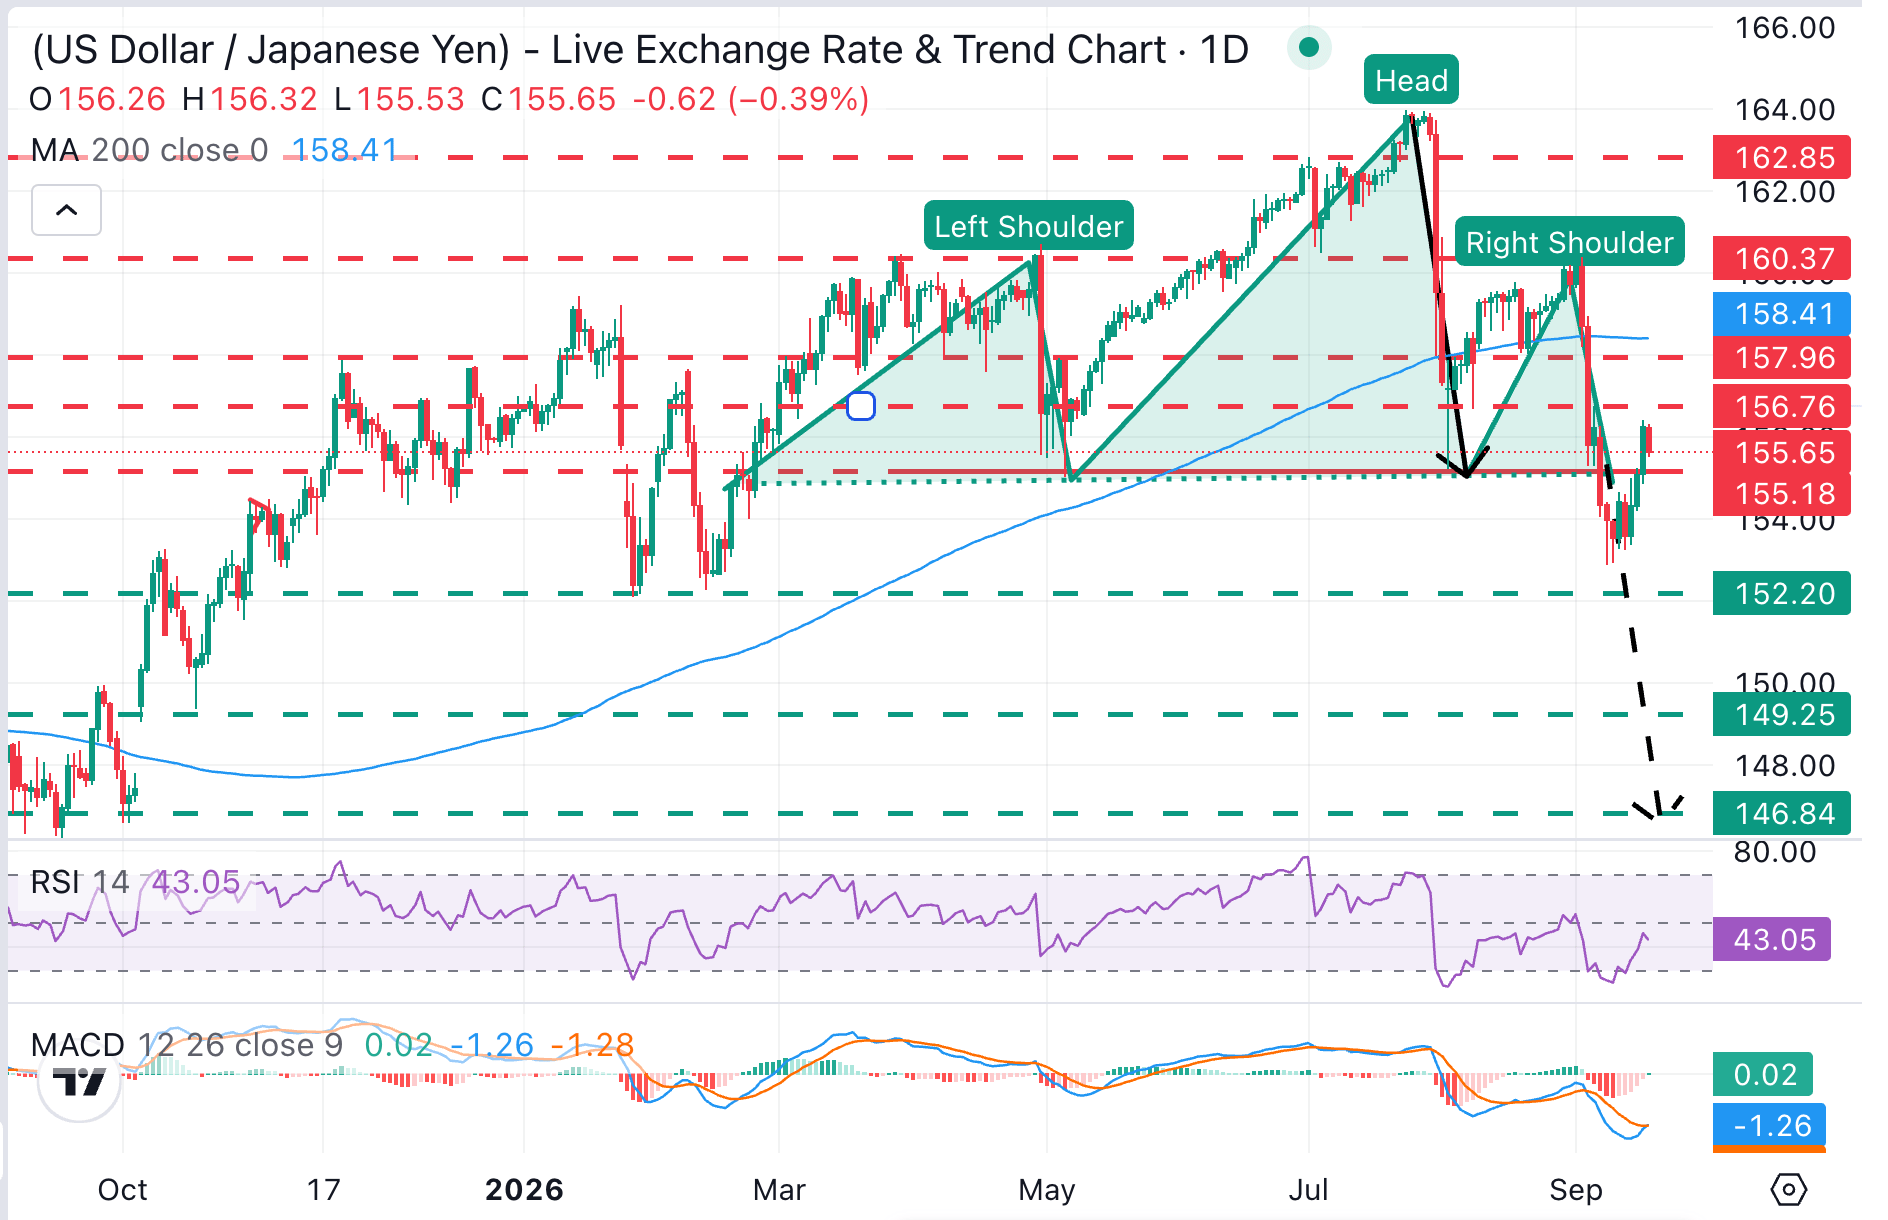
The USD/JPY pair has returned above the neckline of a bearish Head & Shoulders (H&S) pattern, following a post-Fed rally, but is struggling to get past a previous support-turned-resistance at the 156.75 area, which keeps the broader bearish structure in place. Momentum indicators on the daily chart endorse the bearish view, as the Relative Strength Index (RSI) remains below the 50 level and the Moving Average Convergence Divergence (MACD) is below zero, suggesting rallies are likely to find sellers.
Bulls should confirm above the mentioned H&S neckline at 155.20 and the September 4 high at 156.76 to clear the path towards the area between the previous support zone around 158.00 and the 200-day Simple Moving Average (SMA), at 158.41.
A reversal below 155.20, on the contrary, would confirm the H&S formation, adding pressure towards the 2026 lows near 152.00. The H&S’s measured target lies around the October 2025 lows, at 146.60.
Central banks FAQs
Central Banks have a key mandate which is making sure that there is price stability in a country or region. Economies are constantly facing inflation or deflation when prices for certain goods and services are fluctuating. Constant rising prices for the same goods means inflation, constant lowered prices for the same goods means deflation. It is the task of the central bank to keep the demand in line by tweaking its policy rate. For the biggest central banks like the US Federal Reserve (Fed), the European Central Bank (ECB) or the Bank of England (BoE), the mandate is to keep inflation close to 2%.
A central bank has one important tool at its disposal to get inflation higher or lower, and that is by tweaking its benchmark policy rate, commonly known as interest rate. On pre-communicated moments, the central bank will issue a statement with its policy rate and provide additional reasoning on why it is either remaining or changing (cutting or hiking) it. Local banks will adjust their savings and lending rates accordingly, which in turn will make it either harder or easier for people to earn on their savings or for companies to take out loans and make investments in their businesses. When the central bank hikes interest rates substantially, this is called monetary tightening. When it is cutting its benchmark rate, it is called monetary easing.
A central bank is often politically independent. Members of the central bank policy board are passing through a series of panels and hearings before being appointed to a policy board seat. Each member in that board often has a certain conviction on how the central bank should control inflation and the subsequent monetary policy. Members that want a very loose monetary policy, with low rates and cheap lending, to boost the economy substantially while being content to see inflation slightly above 2%, are called ‘doves’. Members that rather want to see higher rates to reward savings and want to keep a lit on inflation at all time are called ‘hawks’ and will not rest until inflation is at or just below 2%.
Normally, there is a chairman or president who leads each meeting, needs to create a consensus between the hawks or doves and has his or her final say when it would come down to a vote split to avoid a 50-50 tie on whether the current policy should be adjusted. The chairman will deliver speeches which often can be followed live, where the current monetary stance and outlook is being communicated. A central bank will try to push forward its monetary policy without triggering violent swings in rates, equities, or its currency. All members of the central bank will channel their stance toward the markets in advance of a policy meeting event. A few days before a policy meeting takes place until the new policy has been communicated, members are forbidden to talk publicly. This is called the blackout period.
Economic Indicator
BoJ Interest Rate Decision
The Bank of Japan (BoJ) announces its interest rate decision after each of the Bank’s eight scheduled annual meetings. Generally, if the BoJ is hawkish about the inflationary outlook of the economy and raises interest rates it is bullish for the Japanese Yen (JPY). Likewise, if the BoJ has a dovish view on the Japanese economy and keeps interest rates unchanged, or cuts them, it is usually bearish for JPY.
Read more.Next release: Fri Sep 18, 2026 03:00
Frequency: Irregular
Consensus: 1.25%
Previous: 1%
Source: Bank of Japan


