


.jpg)
I. Key Snapshot
⚠️ Houthi forces carry out attacks on Riyadh, ratcheting up regional conflict. Washington and Tehran exchange sharp rhetoric. Trump warns Iran will face economic collapse or regime removal if no deal is struck.
🏛️ US 10-year Treasury yield climbs back above 5%. The BOJ lifts rates by 25 bps to 1.25%, the highest level since 1995.
II. Market Outlook
Core Events
- Houthi attacks Riyadh as US-Iran tensions heat up: Houthi strikes target Riyadh and amplify regional risk. Trump warns Iran of economic collapse or regime removal without an agreement. Iran’s military pledges severe retaliation against any fresh assaults. → WTI crude fell 1.58% to $100.30/bbl, up 0.25% week-on-week. Brent crude dropped 0.91% to $103.87/bbl, down 0.71% week-on-week.
Exclusive View
The 10-year US Treasury yield back above 5% plus the BOJ’s most aggressive tightening cycle since the 1990s. Higher global interest rates will continue to weigh on risk assets.
III. Overnight Market Performance
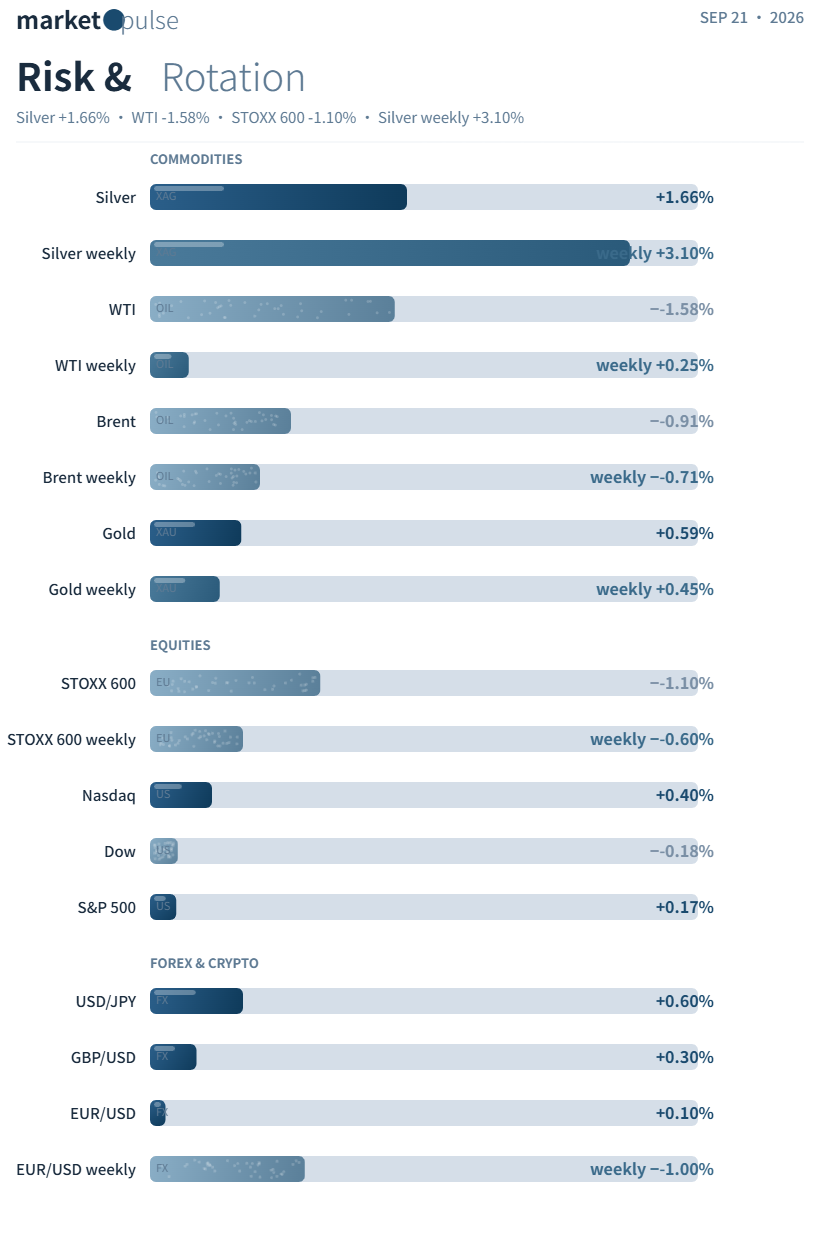
- US Equities: Dow -0.18% at 51682.64; S&P500 +0.17% at 7650.50; Nasdaq +0.40% at 26522.55.
- European Equities: STOXX 600 -1.1% at 635.45, erasing most of prior two-day gains, weekly loss 0.6%.
- Bond Market: US 10Y yield at 5.00%, +5.3 bps; 2Y at 4.743%, +5.3 bps; 30Y +3.6 bps to 5.332%.
- Commodities: WTI Oct crude -1.58% to $100.30/bbl, weekly gain 0.25%. Brent -0.91% to $103.87/bbl, weekly loss 0.71%. COMEX Gold +0.59% to $4385.9/oz, weekly +0.45%. Silver +1.66% to $66.556/oz, weekly +3.1%.
- FX: USD/JPY +0.6% to 156.86, biggest weekly gain since Oct 2025. EUR +0.1% to 1.1483, weekly -1%. GBP +0.3% to 1.3393.
IV. Macro News
1. ⚠️ Houthi attacks Riyadh, US-Iran exchange threats: Trump warns Iran of economic collapse or regime change unless a deal is reached. Iran’s military vows retaliation for any new strikes.
Insight: Rhetoric has escalated to regime-survival stakes. Unpredictable conflict dynamics keep crude trapped in high volatility despite pullbacks.
2. 🛢️ Saudi cuts October long-term crude supply to Europe to zero; European diesel surges past $200/bbl. North Sea crude premium hits record high. Macron plans to convene a G7 summit to coordinate strategic oil reserve releases.
Insight: This marks a clear cut in export capacity, not merely shipping disruptions. Europe faces its worst winter energy risk since the 2022 energy crisis.
3. 🇯🇵 BOJ hikes 25 bps to 1.25%, highest since 1995. Japan’s sharpest tightening cycle since 1990, yen posts its strongest weekly gain since Oct 2025.
4. 📉 US August manufacturing output unexpectedly fell 0.3% MoM vs forecast +0.3%. Elevated oil prices and rising rates partly offset AI-driven capital spending support.
V. Corporate News
1. 🚀 Anthropic delays IPO to November, targeted valuation hits $2 trillion. Annualized revenue to exceed $100bn in 2026.
2. 🤖 OpenAI projected cumulative burn over $278bn by 2030, with revenue target of $350bn in the same period. Capital expenditure among top AI firms keeps surging.
VI. Today’s Focus
· 🇰🇷 South Korea September exports: Key gauge for global trade amid Middle East conflict and tariff pressure.
· 📊 Nasdaq 100 quarterly rebalancing takes effect; SpaceX weight rises to 2.82%.
· 🗣️ Chicago Fed President Goolsbee speech: FOMC voter for 2027, watch for fresh signals on rate path.


