Core Snapshot
· 📉 Large-cap technology stocks tumbled sharply on Thursday. The Nasdaq lost 5.52% to settle at 24,315.00, down 11.9% from its record close on October 6. The Philadelphia Semiconductor Index crashed 12.25%.
· 💾 Nvidia fell more than 9%, AMD slumped over 17%, deepening a brutal autumn for AI trades. The S&P 500 plunged 4.36% and the Dow dropped 3.44%.
· 🛢️ Another oil tanker was attacked near the Strait of Hormuz amid sustained pressure from Iran. WTI rose 2.72% to $90.52 per barrel, while Brent gained 3.88% to $98.29 per barrel.
I. Market Outlook
Key Events
- Big Tech sells off sharply as Nasdaq drops 5.52%: It marked the steepest single-day decline since last year’s Liberation Day rout and amplified the poor performance of AI trades this autumn. The Nasdaq stands 11.9% below its October 6 record close, and the Philadelphia Semiconductor Index fell 12.25% to its lowest level in more than six months.
Exclusive View
The Nasdaq’s 5.52% single-day drop and 11.9% pullback from its peak signal that AI trades have officially entered a technical bear market. Nvidia’s more than 9% fall and AMD’s 17% slump, paired with the semiconductor index’s 12.25% collapse, represent a sharp reckoning over returns from AI capital spending rather than a reaction to one isolated trigger.
II. Overnight Markets
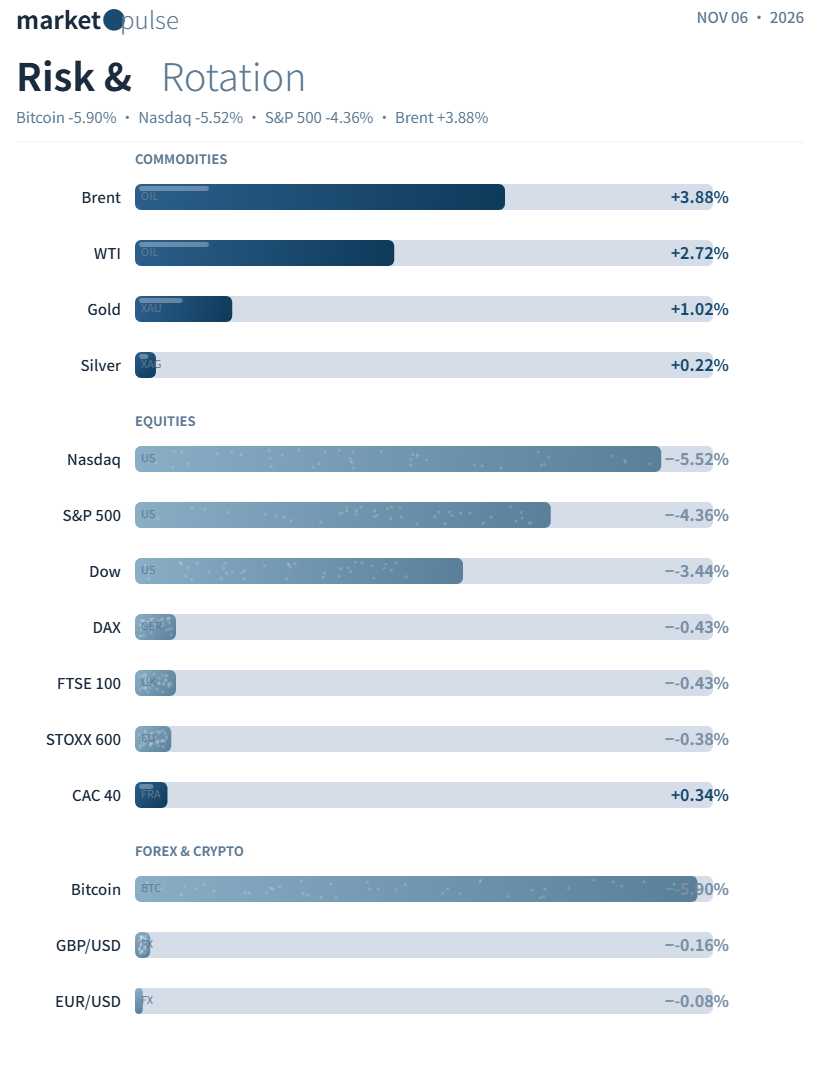
US Equities: S&P 500 plunged 4.36% to 7,353.73; Nasdaq fell 5.52% to 24,315.00; Dow lost 3.44% to 51,523.06.
European Equities: STOXX Europe 600 slipped 0.38% to 654.87. Germany’s DAX fell 0.43%, France’s CAC 40 rose 0.34%, and the FTSE 100 dropped 0.43%.
Fixed Income: The 10-year Treasury yield fell 6.7 basis points to 4.825%; the 30-year yield dipped 3.7 basis points to 5.243%.
Commodities: WTI December crude rose 2.72% to $90.52 per barrel; Brent climbed 3.88% to $98.29 per barrel. COMEX gold gained 1.02% to $4,102.50 per ounce, its highest settlement since October 21. Silver edged up 0.22% to $52.233 per ounce.
FX: The DXY held steady at 101.49. The euro eased 0.08% to 1.1218; sterling fell 0.16% to 1.3449 after touching a more than seven-week high earlier.
Crypto: Bitcoin tumbled 5.90% to $75,679, having dipped as low as $75,616 intraday.
III. Macro Headlines
1. 📉 Big Tech rout pushes Nasdaq 11.9% below its record peak. The index logged its worst day since last year’s Liberation Day sell-off, while the Philadelphia Semiconductor Index sank 12.25% to a six-month low. Nvidia dropped over 9% and AMD slumped more than 17%.
Insight: AI trades have entered a technical bear market. The move reflects broad doubts over returns on AI capital expenditure rather than a single catalyst, with both earnings delivery and borrowing costs weighing on valuations.
2. 🏛️ Two Fed policymakers backed gradual, steady rate hikes to rein in inflation running above target, noting election outcomes could alter price pressures across the US economy.
3. 🛢️ Another tanker attack near the Strait of Hormuz keeps Iranian geopolitical pressure alive. Geopolitical risks flared again after the US midterm elections and lifted crude prices.
4. 📊 US initial jobless claims fell to a 57-year low, while third-quarter labour productivity jumped sharply. Tight labour markets alongside stronger productivity give policymakers grounds to keep rates elevated.
5. 🇬🇧 The Bank of England raised rates to 4.0% for the first time in more than three years and warned further tightening may be needed if US-Iran hostilities persist.
6. 💰 Goldman Sachs cut its gold forecasts, lowering the end-2026 target from $4,650 to $4,150 and the end-2027 target from $5,400 to $4,800 amid a more hawkish Fed stance.
IV. Corporate News
1. 🤖 OpenAI unveiled GPT-6 Cyber, a major leap forward for cybersecurity-focused AI. The model has already helped uncover hundreds of critical vulnerabilities and deepens the practical use of AI in specialised vertical sectors.
V. Key Releases Today
· 🇪🇺 Eurozone September retail sales month-on-month figure.
· 📊 US October non-farm payrolls and unemployment rate. Markets expect 65,000 new jobs and an unemployment rate steady at 4.2%. Against the backdrop of the tech meltdown and Fed officials favouring gradual hikes, this jobs report will directly shape expectations for a December rate rise.
· 📊 Preliminary November University of Michigan consumer sentiment and one-year inflation expectations.