I. Quick Snap
- Jensen Huang has resigned as Nvidia’s CEO, president and board member. The CFO takes over as interim chief executive. Nvidia tumbled as much as 14% during the session and closed down more than 4%, while the semiconductor index eased 0.5%.
- The 10-year US Treasury yield trades around 5.13%, with the two-year yield near 4.88%. Gold fell 2.85% to USD 3,878.40 an ounce, and silver lost 3.68%.
- USD/JPY broke above 160 for the first time since September, weakening for a third straight session and stoking bets on Bank of Japan intervention.
II. Market Outlook
Key Catalysts
- Jensen Huang resigns as Nvidia CEO: Nvidia announced Huang’s immediate departure from the roles of CEO, president and director. The company’s CFO will serve as interim CEO. Nvidia also appointed its first board chair and launched a search for a permanent CEO from internal and external candidates. The stock plunged as much as 14% intraday before paring losses. The major US benchmarks pulled back from one-week highs. The S&P 500 fell 0.35% to 7,592.40, the Nasdaq lost 0.39% to 25,366.09 and the Dow slipped 0.36% to 52,297.09. The semiconductor index retreated 0.5%.
Exclusive View
Huang’s exit marks the most consequential governance shake-up in the history of the leading AI hardware firm. The 14% intraday drop reflects acute investor concern over leadership continuity, though the narrower close of minus 4% shows sentiment stabilized as markets priced in the interim CFO appointment and formal CEO search. This is a pivotal transition point as Nvidia shifts from founder-led control toward institutionalized governance. Near-term volatility is inevitable, while the longer-term trajectory hinges on whether the new chief can preserve the firm’s strategic direction.
III. Overnight Markets
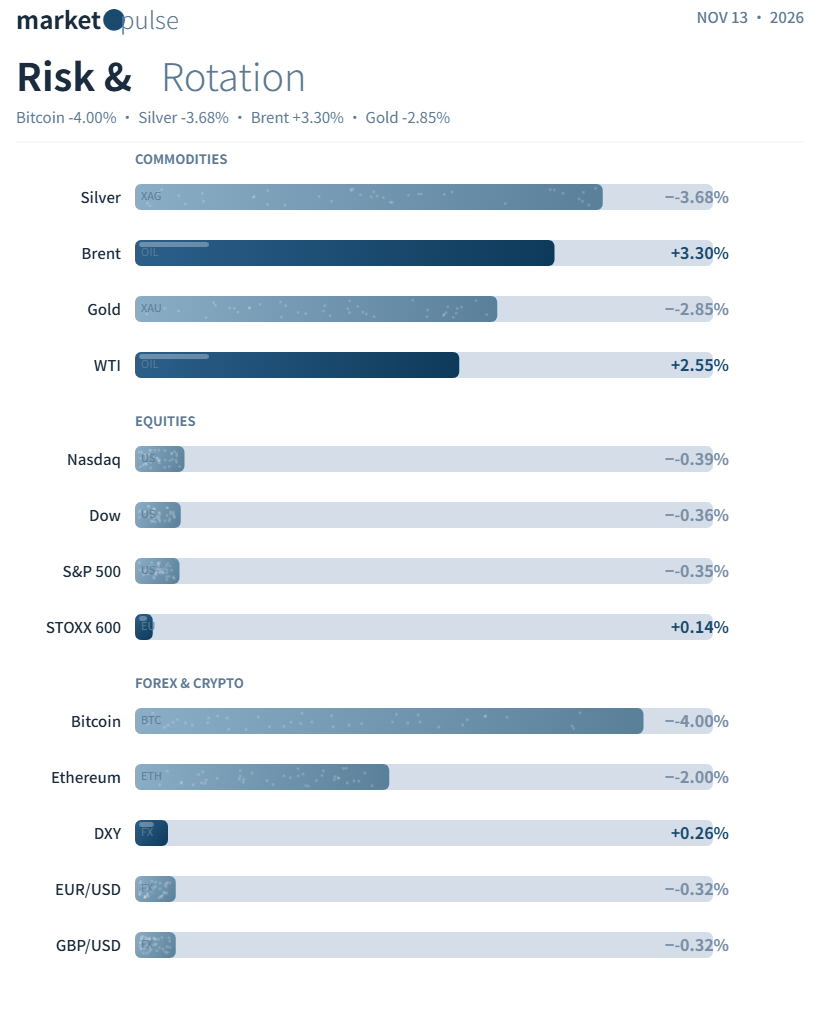
- US Equities: S&P 500 -0.35% at 7,592.40. Dow Jones -0.36% at 52,297.09. Nasdaq -0.39% at 25,366.09. Semiconductor index down 0.5%.
- European Equities: STOXX Europe 600 +0.14% at 664.01.
- Fixed Income: 10-year US Treasury yield around 5.13%; two-year yield near 4.88%.
- Commodities: WTI December crude +2.55% at 88.74 per barrel. Brent +3.30% at 95.82 per barrel. COMEX gold -2.85% to 3,878.40 an ounce. Silver -3.68% at 49.972 an ounce.
- FX: DXY +0.26% to 103.174. EUR/USD at 1.1056, softer from the prior close of 1.1091. GBP/USD at 1.3236, down from 1.3278.
- Crypto: Bitcoin dropped more than 4% intraday and fell below USD 72,000, hitting a two-month low. Ethereum slid over 2% to 2,011.53.
IV. Macro Headlines
- Trump says the United States does not need a deal with Iran, sending crude sharply higher. He added that Vance ought to focus on domestic issues. The remarks erased earlier price weakness built around hopes for diplomatic progress.
Insight: Geopolitical risk remains highly sensitive to political signals. Trump’s comments make clear that a diplomatic path is not assured, keeping oil volatility elevated.
- Mary Daly says additional rate hikes may be needed to bring inflation under control. The San Francisco Fed president voiced explicit support for further tightening.
- The US federal deficit hit USD 404 billion in October, up 42% year over year. Deteriorating fiscal conditions are adding pressure to long-dated yields.
- USD/JPY pushed past 160 for the first time since September. The pair weakened for a third consecutive day and raised the odds of intervention by the Bank of Japan.
V. Corporate News
- Jensen Huang resigned from his posts as CEO, president and director. The CFO was named interim CEO. The board appointed the company’s first chair and opened a CEO search to both internal and external candidates. Nvidia enters a historic shift away from founder leadership toward formal institutional governance.
- Anthropic’s IPO is reported to have drawn roughly six times oversubscribed orders, underscoring robust investor appetite for top-tier AI listings.
- Fresh signs point to tighter AI funding conditions. OpenAI has secured USD 15 billion in its latest fundraising round, versus an original target of USD 30 billion.
- SpaceX plans to invest USD 74 billion to build data centers across Arizona and Texas, expanding the global footprint for compute infrastructure.
VI. Key Events to Watch
- US October PPI. After three straight months of elevated CPI readings, producer-side price pressure will shape expectations for the magnitude of the December rate hike.
- Preliminary November University of Michigan consumer sentiment. Consumer inflation expectations remain a core variable tracked by the Federal Reserve.