


Key Snapshot
· 📉 AI jitters eased, tech stocks lifted S&P and Nasdaq higher. S&P 500 closed at its second-highest level ever, posting a weekly gain above 1%. Nasdaq rose for four straight weeks, its longest winning streak in five months.
· 💵 The US Dollar Index advanced for a fourth consecutive week, marking the longest weekly rally since May 2025.
· 🛢️ Trump said Russia agreed to supply more than 300,000 tons of diesel to US and global markets immediately. Iran warned its military strikes would no longer be confined to the Strait of Hormuz.
I. Market Outlook
Core Events
- AI Sentiment Recovers, Tech Stocks Drive Rebound: AI mood improved after OpenAI clarified its revenue metrics, pushing S&P 500 to a historic second-best close. → Dow Jones +0.83% at 51654.95; S&P 500 +0.59% at 7811.51; Nasdaq +0.64% at 27366.17.
Exclusive View
The four-week rally in the US Dollar Index, the longest stretch in 21 months, shows markets are pricing in more Fed rate hikes. Trump’s announcement on Russian diesel supply adds a new variable to global energy supply balances.
II. Overnight Market Performance
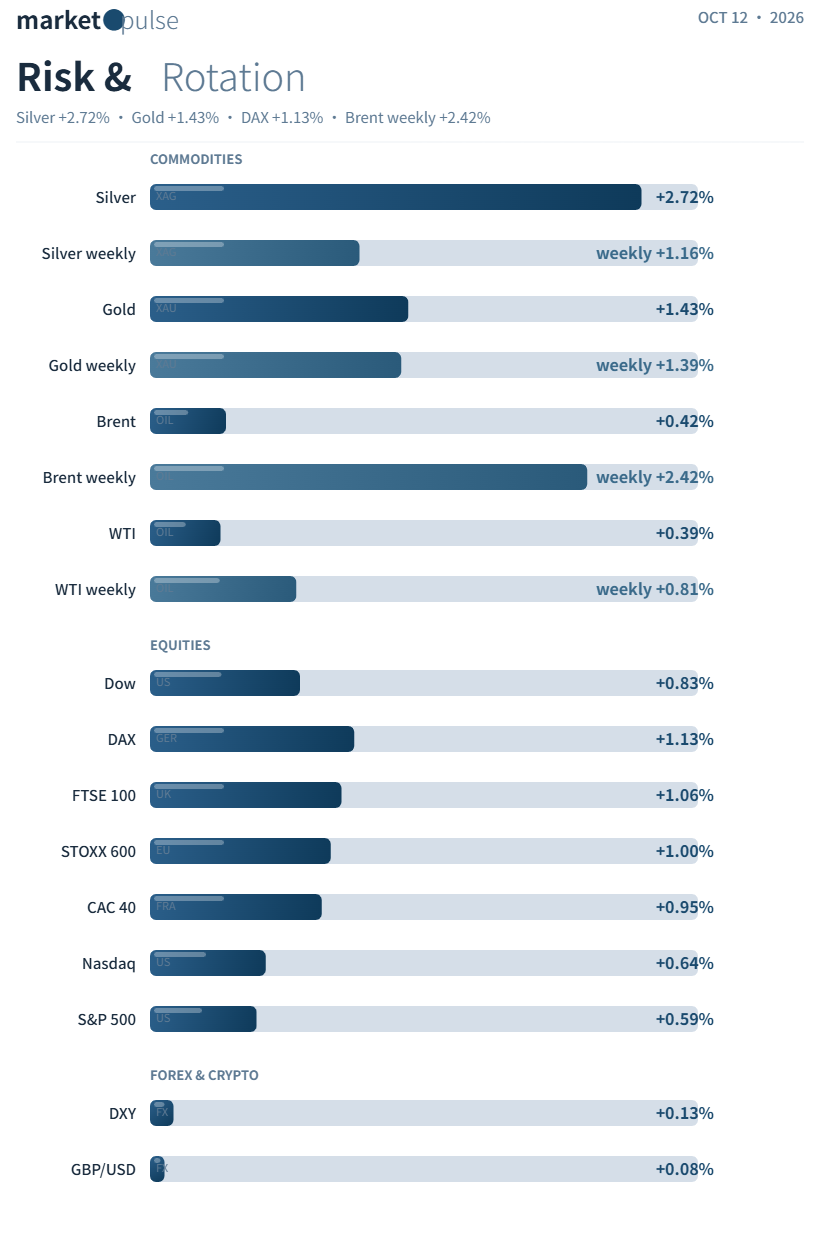
—— US Equities: Dow +0.83% at 51654.95; S&P 500 +0.59% at 7811.51; Nasdaq +0.64% at 27366.17.
—— European Equities: STOXX 600 rose 1%. Germany DAX +1.13%, France CAC 40 +0.95%, UK FTSE 100 +1.06%.
—— Fixed Income: 10-year US Treasury yield climbed 2.8 bps to 5.261%, falling 3.5 bps on the week for its biggest weekly drop in two months. 30-year yield edged up to 5.608%, down 2.9 bps week-on-week.
—— Commodities: WTI Nov crude +0.39% to $91.85/bbl, up 0.81% week-on-week. Brent crude +0.42% to $104.72/bbl, with a weekly gain of 2.42%. COMEX Gold +1.43% to $4191/oz, up 1.39% on the week. Silver +2.72% to $60.67/oz, rising 1.16% week-on-week.
—— FX: US Dollar Index +0.13% to 102.25, notching four straight weekly gains, the longest run since May 2025. Pound Sterling +0.08% to 1.3235 USD, extending its weekly losing streak to seven sessions.
—— Crypto: Bitcoin briefly broke above $83,000.
III. Macro News
1. 🛢️ Trump: Russia Agrees To Ship Over 300,000 Tons Of Diesel Immediately To Global Markets: Trump called his discussion with Putin highly productive, confirming the immediate diesel supply deal.
Insight: Russian diesel exports represent a new supply-side factor. The volume could ease tightness in European diesel markets, though 300,000 tons is modest against global trade volumes. The market impact hinges on further supply expansion.
2. 📉 US Early-October Consumer Confidence Slides Further To 46.3: Middle East tensions pushed up living costs, dragging household economic expectations lower. The index has fallen for three straight months and now sits near the multi-decade low hit in May.
Insight: The divide between robust corporate PMI and weak household sentiment continues to widen. US households face dual pressure from elevated energy prices and high borrowing costs.
3. ⚠️ Iran Hits LPG Vessel, Warns Attacks Are No Longer Limited To Hormuz Strait: Trump cited 28 million barrels of daily oil shipments through the strait, while the two sides remain at odds over shipping security.
IV. Global Corporate News
1. 🤖 OpenAI Clarifies Annualized Revenue: Around $50 billion as of end-September, with a year-end target of $70 billion. Reports point to wide discrepancies in revenue calculation methodology, with actual 2026 revenue projected at only $35 billion, half the annualized target.
The dispute over OpenAI’s revenue accounting will become a core variable shaping AI stock valuations.
2. 📱 Apple Boosts iPhone Duo Orders By 30%; Total iPhone 18 Pro Orders Unchanged: The base Pro model saw a 15% production cut, while Pro Max orders rose 15%. Foldable device demand exceeded internal forecasts.
V. Key Watchlist For Today
· 🌐 IMF and World Bank Annual Meetings (Oct 12–18, Bangkok): Multiple central bank governors will speak. Fed’s Walsh will deliver remarks on rate trajectory and global inflation trends.
· 🇪🇺 EU Foreign Ministers Meeting: Discussions will cover the Russia-Ukraine war and Middle East geopolitical risks.
· 🏆 2026 Nobel Prize in Economics Announcement.






