


【Key Snapshot】
· ⚠️ The US and Iran launched their biggest round of vessel-targeted strikes in six months. Iran sank five US tankers before attacking 10 more ships, sending Brent crude above $100 per barrel.
· 📉 Geopolitical risks and rising rates weighed on risk assets. All three major US equity benchmarks closed lower. Dow Jones fell 0.77% to 52381.02, S&P 500 lost 0.48%, Nasdaq dropped 0.64%.
【I. Market Outlook】
Core Events:
‑ US‑Iran largest maritime clash in six months: Iran stated it attacked 10 vessels near the Strait of Hormuz after US forces sank five Iranian tankers. This marks the largest vessel-focused exchange of fire since hostilities began six months ago, directly fueling a sharp oil rally. → Front-month Brent crude +3.36% at $101.21/bbl, breaking above $100 for the first time in over a month; WTI crude +3.25% at $96.05/bbl, both hitting highs since May.
Exclusive View:
Oil pushing past $100 is a natural outcome of escalating geopolitical risk. The six-month high scale of ship-to-ship strikes signals the conflict is evolving from limited skirmishes toward full-blown maritime confrontation.
【II. Overnight Market Performance】
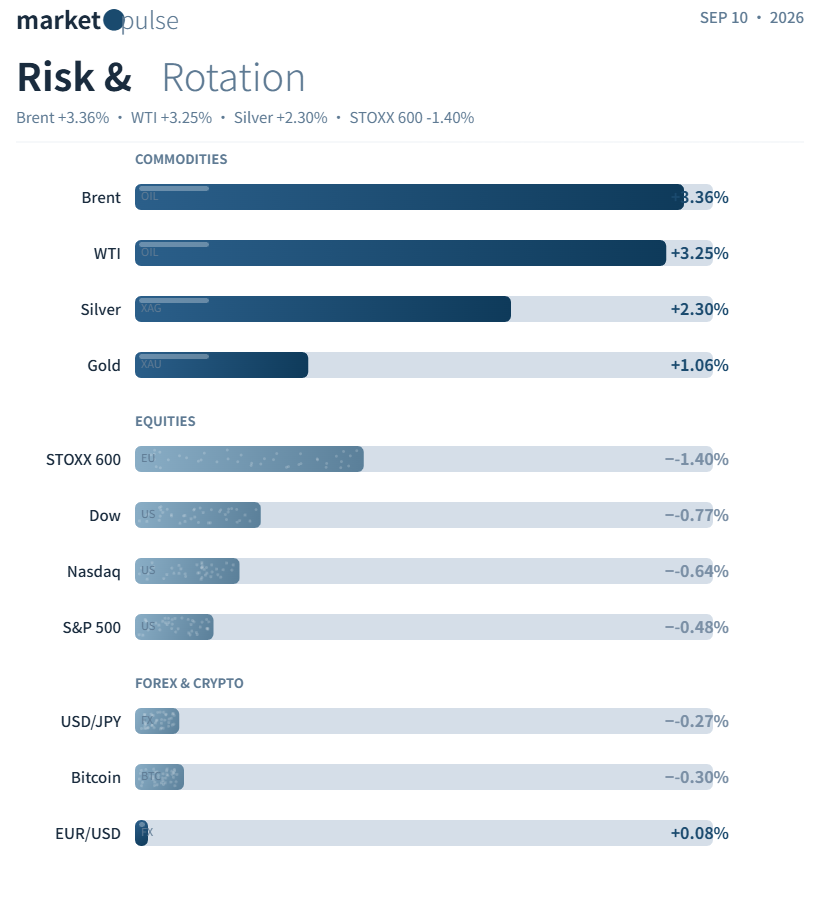
‑ US Equities: S&P 500 -0.48% at 7636.46; Nasdaq -0.64% at 26253.34; Dow Jones -0.77% at 52381.02.
‑ European Equities: Pan-European STOXX 600 fell 1.4% to 640.41, hitting the lowest level since late July.
‑ Fixed Income: US 10-year Treasury yield rose 3.06 bps to 4.835%, the highest since November 2023; 30-year yield +2.06 bps to 5.2846%; 2-year yield +2.52 bps to 4.423%.
‑ Commodities: Front-month Brent crude +3.36% at $101.21/bbl, above $100 for first time in more than a month; WTI +3.25% at $96.05/bbl, both May highs. Spot gold +1.06% at $4401.77/oz; silver gained roughly 2.3%.
‑ FX: US Dollar Index flat at 98.83. EUR/USD edged up 0.08% to 1.1632, near two-week highs. USD/JPY -0.27% to 153.54, close to seven-month lows.
‑ Crypto: Bitcoin -0.3% at around $78,200.
【III. Macro News】
1. ⚠️ US and Iran stage largest maritime attacks in six months, crude tops $100. Iran said it struck 10 vessels near the Strait of Hormuz after US forces sank five Iranian tankers. It is the biggest exchange of strikes targeting ships since the war started, and Brent crude breached $100 for the first time in over a month.
Insight: Maritime hostilities between the US and Iran have escalated from limited friction into full confrontation. Shipping safety in the Strait of Hormuz faces material threats. Oil above $100 is importing inflationary pressure globally.
2. 🏛️ US 10-year Treasury yield climbs past 4.84%, highest since Nov 2023. The expanded US Treasury long-dated buyback program launched on its first trading day with a $6bn purchase volume, only hitting the lower end of market estimates. Disappointment pushed long-end yields higher. The EIA also revised up oil price forecasts for this year and next, putting the 2026 average Brent projection near $91/bbl.
3. 🏛️ ECB rate decision due today, 25bp hike widely priced in. Markets expect the deposit facility rate to rise to 2.50%. Eurozone August CPI surged to 3.3%, and persistent energy gains make a hike almost certain.
4. 📊 US August PPI and initial jobless claims on tap today. Consensus sees headline PPI rising 5.3% YoY and 0.4% MoM; core PPI up 4.7% YoY. Initial jobless claims forecast at 205k versus prior 206k. These readings, paired with tomorrow’s CPI, will shape Fed September rate bets.
【IV. Corporate News】
1. 📱 Apple launches Duo foldable phone priced at $1,999. This represents Apple’s biggest flagship overhaul in years. The foldable segment now sees a three-way rivalry among Apple, Samsung Electronics and Huawei.
【V. Key Events To Watch】
· 🏛️ ECB monetary policy decision. Markets widely expect a 25bp hike lifting deposit rate to 2.50%, followed by President Lagarde’s press conference.
· 📊 US August PPI report. Consensus: 5.3% YoY, 0.4% MoM. This together with tomorrow’s CPI will steer Fed September policy outlook.
· 📊 US initial jobless claims for week ending Sep 5. Market estimate: 205k.
· 📊 EIA Monthly Short-Term Energy Outlook. The agency already lifted crude price projections; watch revisions to global inventories and supply-demand balances.
· 📊 OPEC Monthly Oil Market Report. With traders focused on US‑Iran conflict and falling stockpiles, monitor adjustments to global demand forecasts.


