I. Quick Snap
- US October CPI climbed 0.4% month-on-month, the third straight reading at or above 0.4% and ahead of the 0.3% consensus. Waller argued the Fed should consider a 50-basis-point increase if inflation fails to cool as projected.
- The three major US equity benchmarks closed lower, with the Nasdaq falling 0.74% to 25065.87. Gold lost 2.0% and silver dropped 2.78%. Bitcoin retreated 3.06%, and leveraged liquidations topped USD 630 million over the prior 24 hours.
II. Market Outlook
Key Catalysts
- US October CPI beats estimates, 50 bp hike becomes a live option: Headline CPI rose 0.4% month-on-month for a third consecutive month, exceeding the 0.3% forecast. Fed Governor Waller backed a December rate increase and said policymakers ought to weigh a half-point hike should inflation stay sticky. The two-year Treasury yield jumped 18.7 bps to 4.73%, the ten-year yield rose 12.6 bps to 4.99%, and the US Dollar Index gained 0.57% to 102.26.
Exclusive View
Three consecutive firm CPI prints confirm inflation is far stickier than priced in. Waller’s explicit inclusion of a 50-basis-point hike is the critical policy signal from this release: the December FOMC is no longer only a question of whether to hike, but by how much. Brent dipped below USD 90 a barrel intraday for the first time since August. The contrast between sliding crude and persistent inflation shows the main driver of price pressure has shifted away from energy and toward core services.
III. Overnight Markets
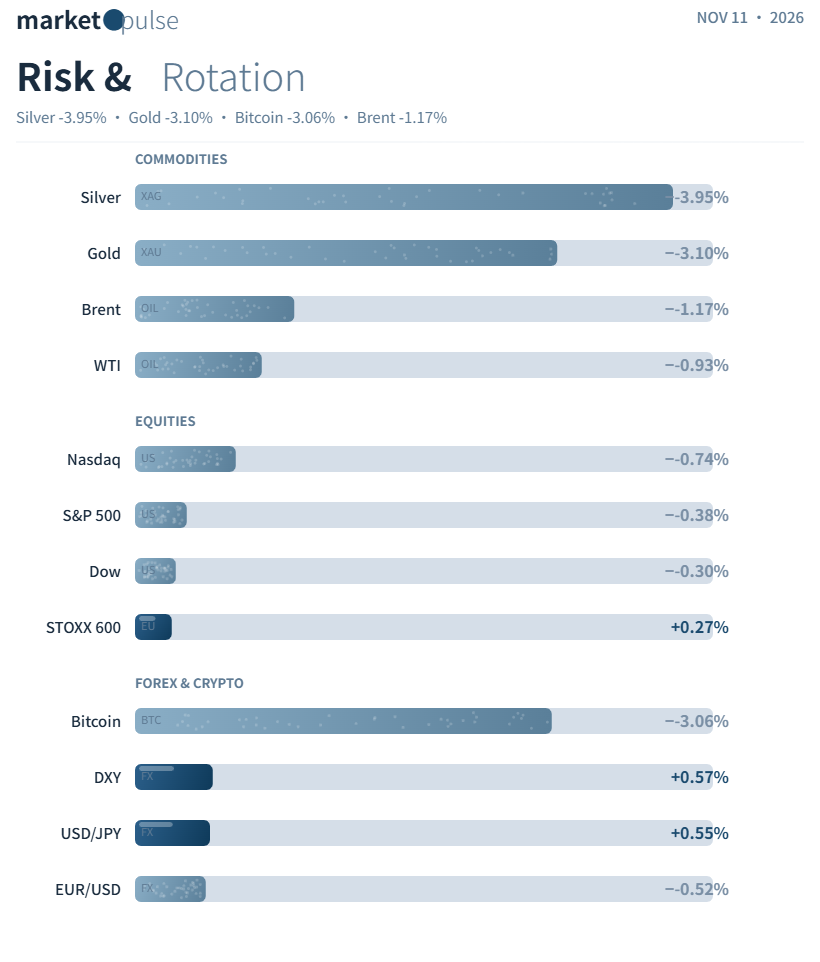
- US Equities: Dow Jones -0.30% at 52231.89. S&P 500 -0.38% at 7520.93. Nasdaq -0.74% at 25065.87.
- European Equities: STOXX 600 +0.27% at 658.32.
- Fixed Income: Two-year US Treasury yield +18.7 bps to 4.73%, its highest since October 28. Ten-year yield +12.6 bps to 4.99%, the strongest level since October 29.
- Commodities: WTI December crude -0.93% at 86.04 per barrel. Brent -1.17% at 91.49, breaking below 90 intraday for the first time since August. COMEX gold -2.0% to 4030.20 an ounce; spot gold dipped nearly 3.1% intraday. Silver -2.78% at 51.101 an ounce, with spot silver down 3.95%.
- FX: DXY +0.57% to 102.26. EUR/USD -0.52% to 1.1223. USD/JPY +0.55% to 157.90.
- Crypto: Bitcoin -3.06% at 73052.90, touching an intraday low of 72736. Total leveraged liquidations across markets surpassed USD 630 million in 24 hours, with longs accounting for USD 511 million.
IV. Macro Headlines
- US October CPI rises 0.4% month-on-month for the third month running, beating the 0.3% forecast and underscoring sticky inflation.
Insight: The run of strong prints confirms inflation momentum has rotated out of energy and into core services. This is the direct trigger for speculation over a larger December hike.
- Waller: He supports a December hike and says a 50-basis-point move deserves consideration if inflation does not cool as expected. This marks the first time a Fed official has publicly put a half-point hike squarely on the table, leaving the size of the December move open.
Insight: Policy uncertainty has moved past “hike or not” to “how large the hike will be”, a more disruptive force for front-end rates and the dollar.
- Russia and Ukraine held peace talks in Abu Dhabi, their first such meeting since February. Rubio described the session as highly productive.
Insight: The resumption of direct negotiations signals marginal easing of geopolitical risk.
V. Corporate News
- The fallout from Jensen Huang’s personal controversy continues. Nvidia has erased USD 470 billion in market value across two sessions, as governance risk evolves from headlines into tangible valuation pressure.
- Anthropic’s IPO is set to raise up to USD 64.4 billion. Shares will be marketed in an indicative range of USD 70 to USD 78 apiece, putting the valuation of one of the sector’s leading AI firms to the market test.
- CoreWeave’s third-quarter revenue surged 168%, beating estimates, and the company lifted its full-year guidance. Management noted tight compute supply has enabled steep price increases, with capacity for next year nearly sold out.
- SoftBank posted its first quarterly loss in two years. The Vision Fund took heavy hits amid the AI sell-off, with large write-downs on US datacenter assets showing AI repricing rippling through venture portfolios.
VI. Key Events to Watch
- Germany’s final October CPI year-on-year print.
- ECB President Lagarde speaks at a forum. With eurozone inflation running at a three-year high, her remarks will shape expectations for the December policy decision.
- US Treasury markets closed for Veterans Day, while equities trade normally.