


Key Snapshot
· 🕊️ Trump rejected Iran’s proposal to reopen the Strait of Hormuz and end hostilities. Iran insists only diplomacy can resolve the conflict, yet Trump leaves room for diplomatic negotiations.
· 📊 US Treasury selloff paused after four straight weeks of losses. The 10-year Treasury yield hit a fresh high since 2007 intraday before pulling back, while the 30-year yield settled at 5.486%.
· 📈 Major US indices closed higher on Friday. S&P 500 rose 1.2% for the week and Nasdaq gained 2%. US August core capital goods orders jumped 1.6% month-on-month, far exceeding forecasts.
I. Market Outlook
Core Events
- Trump rejects Iran’s proposal while retaining diplomatic room: Trump turned down Iran’s proposal to reopen the Strait of Hormuz and end the conflict. Iran stated on Sunday that diplomatic negotiation remains the only viable solution. Still, Trump signalled more talks between US negotiators this week. Iran said mediators have not formally delivered Washington’s rejection, and Tehran will adjust its stance based on the mediator’s final feedback. → WTI crude fell 2.33% to $92.41 per barrel, down 3.8% week-on-week. Brent crude dropped 2.14% to $104.32 per barrel, with a weekly gain of 0.43%.
- Treasury selloff eases but bonds still suffered weekly losses: The 10-year US Treasury yield hit an intraday peak unseen since 2007 before retreating, marking four consecutive weeks of rises. The 30-year yield stood at 5.486%. → S&P 500 rose 0.51% to 7743.41, up 1.2% for the week. Nasdaq climbed 0.48% to 27068.72, posting a 2% weekly gain. Dow Jones advanced 0.93% to 51828.62.
Exclusive View
US August core capital goods orders surged 1.6% month-on-month, well above the 0.5% estimate. July’s reading was revised sharply higher, with a year-on-year increase of 10.6%. The data suggests corporate equipment spending driven by AI infrastructure investment may maintain strong growth for the third consecutive quarter, serving as fresh evidence of economic resilience backing hawkish rate expectations.
II. Overnight Market Action
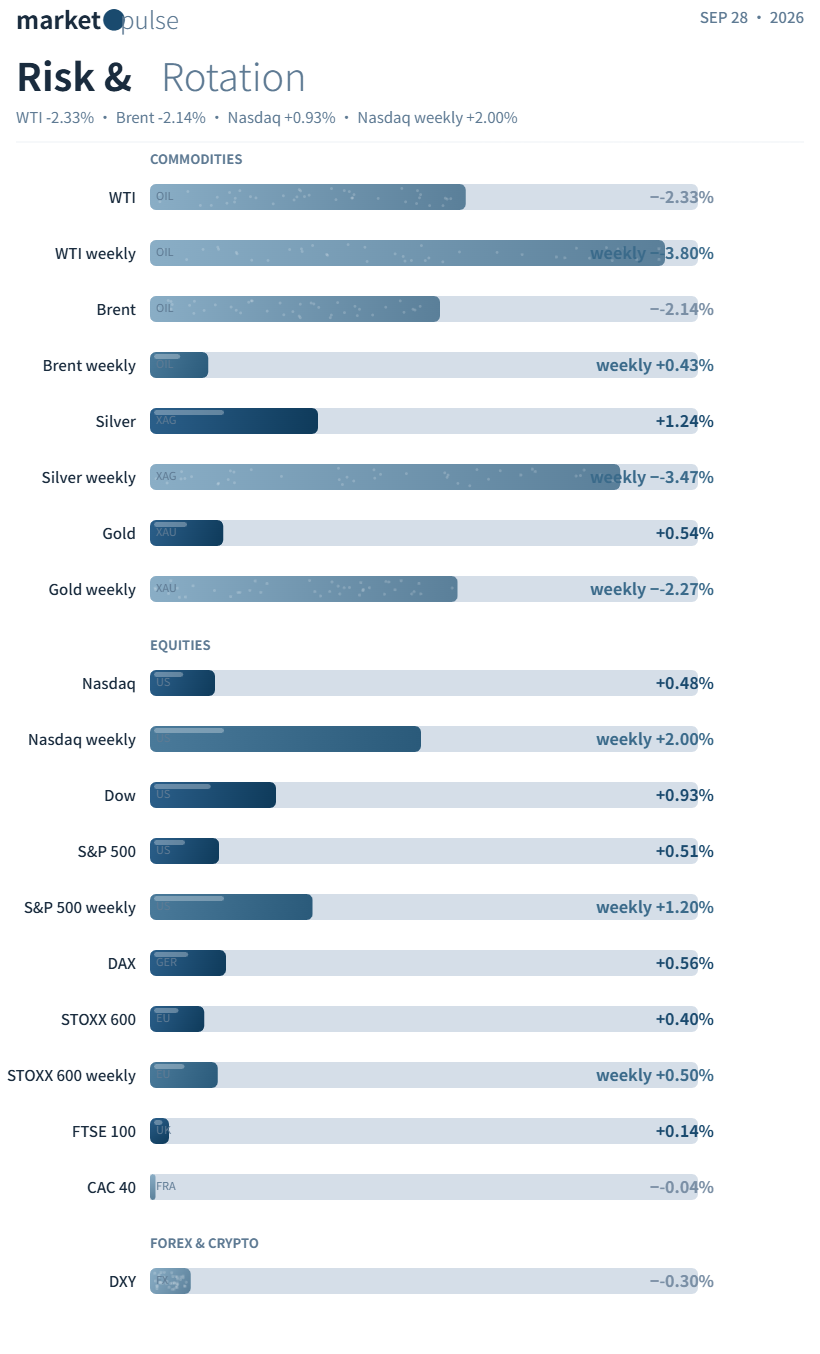
—— US Equities: S&P 500 +0.51% at 7743.41, weekly +1.2%; Nasdaq +0.48% at 27068.72, weekly +2%; Dow Jones +0.93% at 51828.62.
—— European Equities: Pan-European STOXX 600 rose 0.4%, marking its best weekly gain since early August at +0.5%. German DAX gained 0.56%, French CAC 40 edged down 0.04%, UK FTSE 100 rose 0.14%.
—— Fixed Income: 30-year US Treasury yield +2.4 bps at 5.486%; 10-year yield +0.3 bps at 5.165%.
—— Commodities: WTI Nov crude -2.33% to $92.41/bbl, weekly -3.8%; Brent crude -2.14% to $104.32/bbl, weekly +0.43%. COMEX Gold +0.54% to $4286.2/oz, weekly -2.27%; Silver +1.24% to $64.245/oz, weekly -3.47%.
—— FX: US Dollar Index fell 0.3% to 100.95, its largest single-day drop in roughly three weeks, though it rose for the second straight week.
III. Macro Headlines
1. 🕊️ Trump rejects Iran proposal but keeps diplomatic option open: Trump rejected Iran’s proposal to reopen the Strait of Hormuz and end fighting. Iran maintains that diplomacy is the only path to resolve the conflict. Trump still expects US negotiators to hold more consultations this week.
Insight: Both sides are bargaining for a stronger starting position before talks, rather than fully closing diplomatic channels. Mediators have not formally relayed Washington’s rejection to Iran, leaving Tehran’s final stance uncertain.
2. 📊 US August core capital goods orders jump 1.6% MoM, beating estimate of 0.5%: July data was revised sharply upward with 10.6% YoY growth. The reading shows corporate capital expenditure on AI infrastructure may sustain robust expansion for the third quarter in a row.
Insight: Strong core capital goods orders are direct proof that AI capital spending is translating into real economic activity. This supports the Fed’s case for further rate hikes from the demand side.
3. 🕊️ Putin: All solutions to Russia-Ukraine war remain on the table: Russia will weigh its national interests, and signals for Russia-Ukraine peace talks persist.
IV. Global Corporate News
1. 🤖 OpenAI mulls $500 “Pro Max” tier, prioritising fast Work and Codex with potential Cerebras compute access: Pricing segmentation in AI application layer is accelerating. High-end computing power and model capability become core premium drivers.
2. 💾 Musk: Nvidia chips deployed in Colossus 2 may double by year-end; Tesla Optimus production capacity up 10x, targeting 1,000 robots weekly by year-end: AI compute expansion and mass production of humanoid robots advance in tandem.
V. Key Events To Watch
· 📊 Bank of Japan July Monetary Policy Meeting Minutes: After the 25bp rate hike to 1.25% in September, the minutes will reveal divisions among policymakers over future rate paths.
· 🗣️ ECB President Lagarde’s quarterly monetary policy testimony to European Parliament: With ongoing energy shocks and upside inflation risks, Lagarde’s remarks will shape market pricing for further ECB rate hikes.
· 🚀 SpaceX Starship 24th flight test: Following its first post-listing earnings report and share price volatility, Starship test progress is critical for SpaceX valuation.


