


For Q2 2026, the estimated neutral rate in the U.S. is 1.01%. Meanwhile, the June SEP shows FOMC members expect core PCE inflation to reach 3.3% by the end of 2026, putting the implied nominal neutral rate at around 4.31% (red line in the chart).
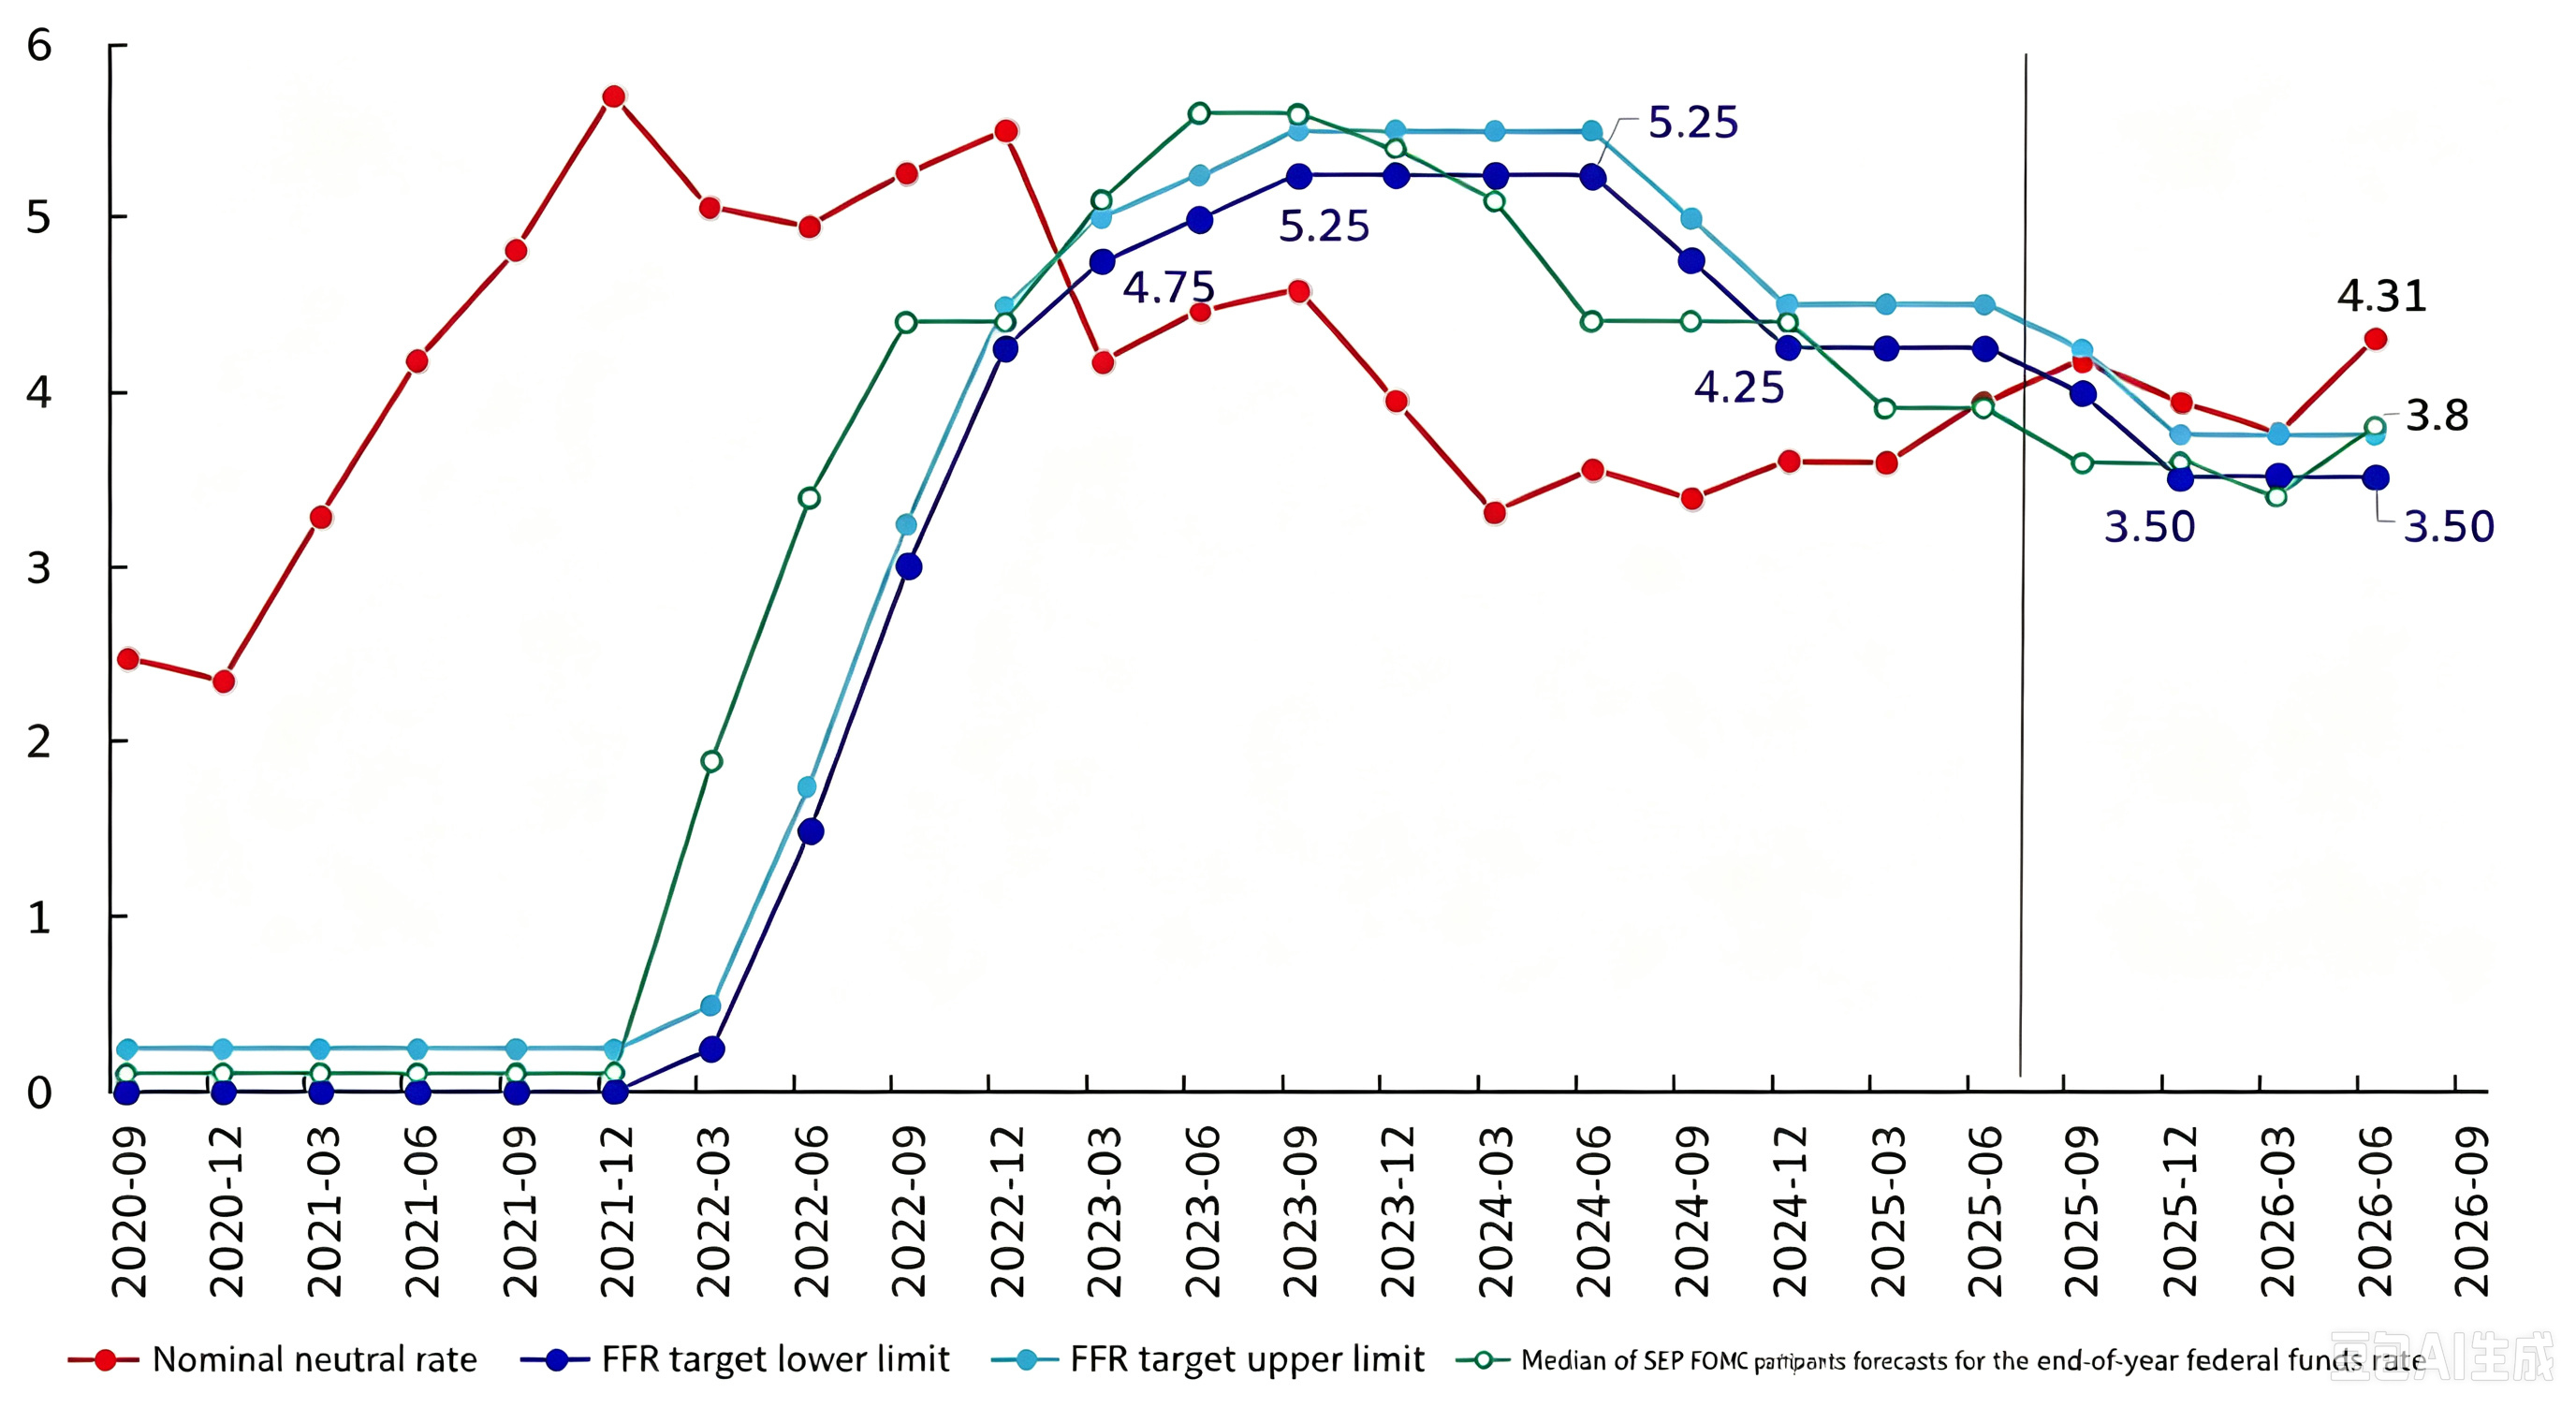
The current federal funds target range is 3.50%–3.75% (blue line), meaning rates are already 0.56–0.81 percentage points below the nominal neutral rate — roughly equivalent to another two to three rate hikes.
But that does not mean the FOMC will simply deliver two or three consecutive hikes. Policymakers are likely to reassess the inflation and labor-market data after each move.
That makes the likely path fairly straightforward:
1. September 16: The Fed hikes once, then pauses to assess the impact on inflation and the labor market. Several FOMC members could dissent.
2. October 29: No rate hike.
3. December: If core PCE inflation and the Fed’s inflation outlook have not eased meaningfully, while the labor market remains resilient, the Fed could deliver another hike.
4. Otherwise: If core PCE continues to cool, the FOMC lowers its 2027 core PCE forecast, or the labor market weakens, the Fed is likely to hold rates and wait for more data.
So, despite the renewed rate-hike expectations, this is not necessarily the start of a new tightening cycle.
It may simply be the Fed making one more move — and then waiting to see what happens next.


