Headlines
U.S. producer prices rose 6.5 percent year-over-year in October, the steepest annual gain since late 2022, while the monthly print came in at 0.3 percent, firming bets that the Federal Reserve may resume rate hikes.
Nvidia and semiconductor stocks weighed on U.S. equities. The S&P 500 closed 0.40 percent lower and the Nasdaq dropped 0.91 percent, though all three benchmarks posted solid weekly gains.
Treasury yields surged, with the 10-year note settling at 5.149 percent, marking its largest weekly advance since the tariff turbulence of 2025.
Market Outlook
The hot PPI reading has reset valuation benchmarks across asset classes. Even with equities finishing the week higher, investors are repricing for a higher-for-longer rate regime. The persistent weakness across AI hardware signals the sector is still undergoing a painful valuation reset. Bessent’s public push for an outside chief executive at Nvidia represents an unusual intervention into the governance of a strategically critical tech firm.
Overnight Markets
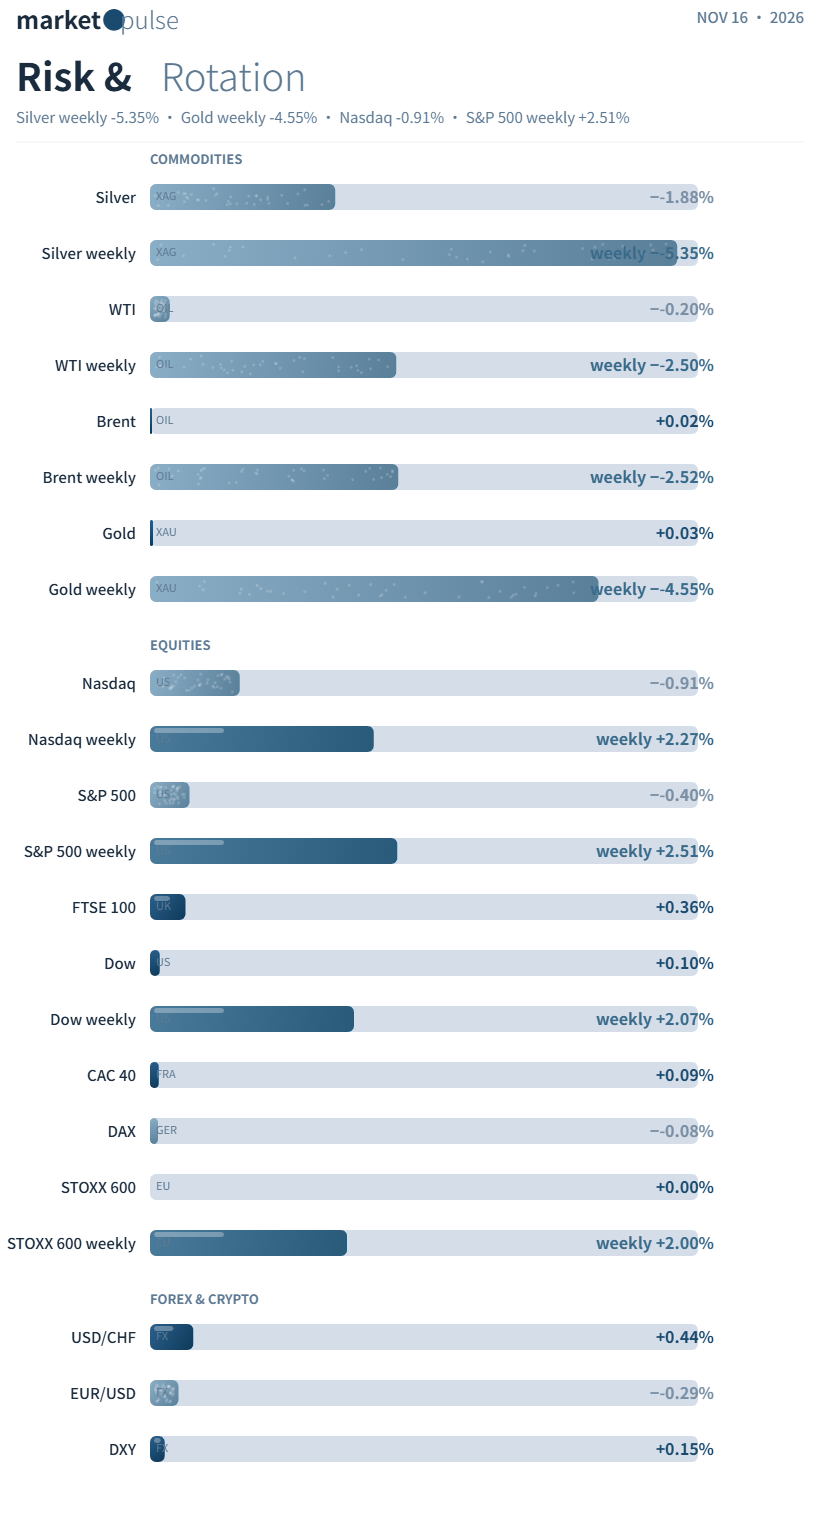
US Equities: Dow +0.10% to 52,347.55; S&P 500 -0.40% to 7,561.67; Nasdaq -0.91% to 25,136.27. For the week, the S&P 500 gained 2.51 percent, the Nasdaq 2.27 percent and the Dow 2.07 percent.
European Equities: STOXX 600 flat at 664.14, up more than 2 percent week-to-date. DAX -0.08%, CAC 40 +0.09%, FTSE 100 +0.36%.
Fixed Income: Two-year Treasury yield edged up to 4.867 percent, while the 10-year yield jumped to 5.149 percent.
Commodities: WTI crude fell 0.20 percent to $88.56 a barrel; Brent crude ticked 0.02 percent higher to $95.84. Gold settled at $3,879.7 per troy ounce, silver at $49.031. Both precious metals suffered sharp weekly losses.
FX: USD/JPY hovered near 160, keeping traders alert for official intervention. EUR/USD slipped 0.29 percent to 1.1021, while the U.S. Dollar Index rose 0.15 percent to 103.37.
Macro News
U.S. October PPI surged 6.5 percent year-over-year, reinforcing sticky inflation pressures across both consumer and production channels. Bond investors are rapidly pricing in a more hawkish Fed.
IEA’s monthly report says the global oil market is swinging back into surplus in the fourth quarter, as OPEC+ supply recovers and demand momentum softens.
Microsoft’s Outlook, Teams and broader Microsoft 365 suite suffered a widespread global outage. The company ruled out a cyberattack as the trigger.
Corporate News
Treasury Secretary Bessent said Nvidia must look externally for its next CEO. Reports say the board has sounded out Arm chief Rene Haas, though Nvidia stated no formal candidate talks have taken place.
OpenAI disbanded its dedicated in-house robotics team, after concluding that frontier foundation models such as GPT-6 Astra can power physical AI without purpose-built robotics models.
What to Watch Today
A Fed task force on productivity and employment holds a hearing, with Fed Chair Walsh scheduled to deliver opening remarks. His tone will guide market pricing for the December policy meeting.