


U.S. producer prices rose 0.4% in August, pushing annual PPI inflation up to 5.4% from 4.8% a month earlier. The increase was heavily influenced by energy costs, with final-demand energy prices jumping 4.2% and diesel prices surging 24.1% during the month.
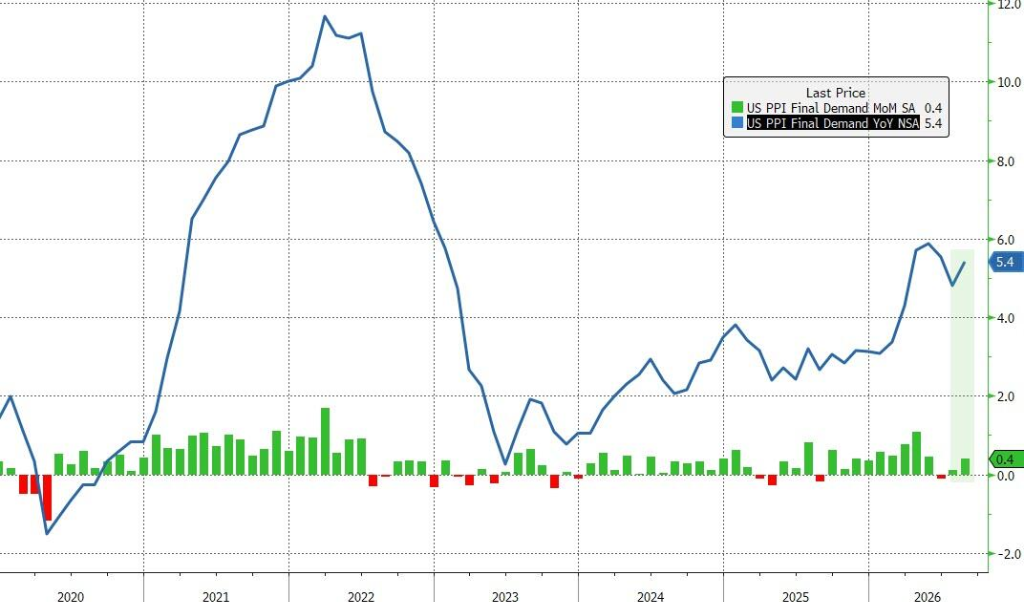
The data has already shifted the policy debate. Markets are now pricing a roughly 70% chance of a Federal Reserve rate hike next week, while Friday’s CPI report could provide another important signal on whether inflationary pressure is broadening beyond energy.
But this is where the picture becomes more complicated.
Higher rates can weaken demand, but they cannot produce more oil. If energy remains a major source of inflation, monetary tightening may have limited power to address the original shock. At the same time, core producer prices are still rising, suggesting the Fed cannot simply dismiss the risk as a temporary energy effect.
That leaves the Fed facing an uncomfortable choice. Tightening policy could help contain second-round inflation pressures, but it cannot bring down oil prices or fix the supply shock driving a large part of the latest increase.
That is the real policy dilemma: the Fed may need to raise rates to stop an energy shock from becoming a broader inflation problem, even though higher rates cannot solve the energy shock itself. In other words, the medicine may slow the economy without treating the original cause of the inflation.
For markets, that makes the inflation outlook more complicated than a simple “hotter data means higher rates” story. If energy remains the main driver, another rate hike could curb demand while doing little to bring the source of price pressure under control.


