I. Quick Snap
- A bounce in AI trading sentiment drove a US stock rebound. Strong CoreWeave results and red-hot demand for the Anthropic IPO eased worries over AI infrastructure. The Nasdaq rose 1.60% to 25466.19, while the S&P 500 climbed 1.31% to 7619.38.
- Sources say Nvidia’s board held a Wednesday meeting to discuss whether to remove CEO Jensen Huang.
- Goldman Sachs, Nomura and Deutsche Bank all revised their Fed rate forecasts higher on the same day. Markets are fully pricing a 25-basis-point hike in December, and gold slipped below USD 4,000.
II. Market Outlook
Key Catalysts
- AI sentiment rebound fuels US equity rally: Better-than-expected CoreWeave earnings and blockbuster demand for the Anthropic IPO helped calm investor concerns around AI infrastructure. Tech and energy led gains across the S&P 500. The Nasdaq closed up 1.60% at 25466.19, the S&P 500 rose 1.31% to 7619.38, and the Dow added 0.49% to 52486.49.
- Nvidia board reportedly debates removing Jensen Huang: People familiar with the matter said directors met on Wednesday to consider ousting the CEO. Governance risks escalated sharply, though broader relief across AI names offset the negative headline.
Exclusive View
AI stocks staged a meaningful recovery after a technical bear market. CoreWeave’s robust print and heavy oversubscription for Anthropic’s IPO serve as the core catalysts, showing that underlying demand for AI infrastructure and capital market appetite remain intact. Still, the board discussion over Huang marks an extreme escalation of governance risk. If confirmed, it would become the single largest source of uncertainty for the AI complex. With three major banks lifting their Fed rate outlooks and gold breaking below USD 4,000, macro tightening expectations keep building.
III. Overnight Markets
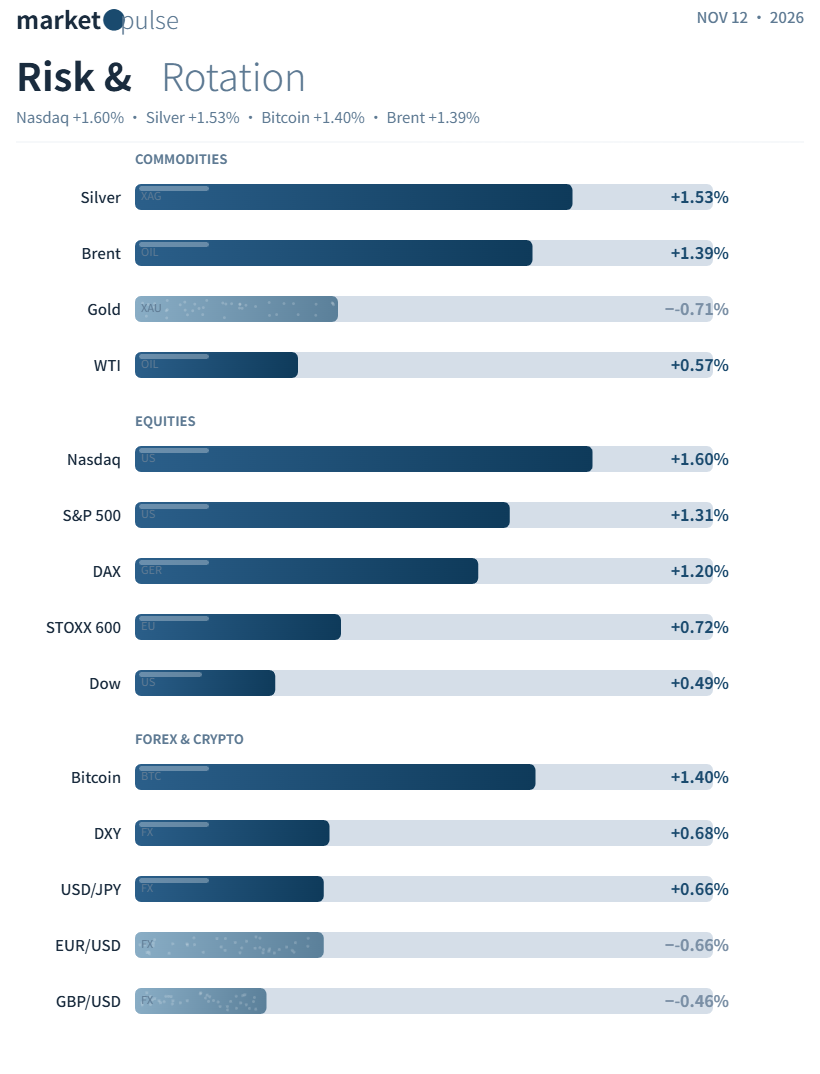
- US Equities: Dow Jones +0.49% at 52486.49. S&P 500 +1.31% at 7619.38. Nasdaq +1.60% at 25466.19.
- European Equities: STOXX 600 +0.72% at 663.05. Germany’s DAX gained 1.2%, hovering near record highs.
- Fixed Income: US Treasury markets were closed for the holiday.
- Commodities: WTI December crude +0.57% at 86.53 per barrel. Brent +1.39% at 92.76 per barrel. COMEX gold -0.71% to 3992.00 an ounce. Silver +1.53% at 51.881 an ounce.
- FX: DXY +0.68% to 102.90. USD/JPY +0.66% to 159.77, hitting a more than two-month high and closing in on 160. EUR/USD -0.66% to 1.1089. GBP/USD -0.46% to 1.3280.
- Crypto: Bitcoin traded near USD 74,300, up roughly 1.4% over 24 hours.
IV. Macro Headlines
- Peace talks between Russia and Ukraine in Abu Dhabi yielded modest progress, though major divides persist. The two-day negotiations moved forward, yet US mediators noted deep mistrust and unresolved sticking points including territorial claims.
- OPEC+ pumped 41.23 million barrels per day in October, equal to 97% of levels before the Iran conflict. Output rose about 2.04 million bpd from September, led by sharp increases from Saudi Arabia. The supply recovery continues to cap oil prices.
- Goldman Sachs, Nomura and Deutsche Bank all upgraded their Fed rate forecasts. Markets now fully price a 25-basis-point hike in December, which pulled gold below USD 4,000. The coordinated revision signals a growing consensus around tighter policy.
V. Corporate News
- Nvidia’s board reportedly convened to discuss removing CEO Jensen Huang, pushing governance risk into an extreme scenario. If verified, the development would represent the biggest standalone risk for AI equities.
- Anthropic’s IPO drew overwhelming investor interest, with subscriptions many times over the offering size for a target valuation of USD 1.4 trillion. The frenzy stands in sharp contrast to Nvidia’s governance turmoil.
- OpenAI’s Q3 revenue fell short of estimates, while losses came in well above consensus. Internal projections see revenue reaching USD 190–200 billion by 2028, underscoring persistent profitability pressure among leading AI firms.
VI. Key Events to Watch
- UK preliminary Q3 GDP.
- US initial jobless claims. Consensus sits at 195,000 versus the prior reading of 189,000.
- US pending home sales annualized for October. Forecast at 3.85 million, down from 3.99 million previously.
- EIA weekly crude oil inventories, delayed by one day due to the Veterans Day holiday.