
Key Snapshot
· 🏛️ The Fed kept the federal funds target range unchanged at 3.75%-4.00%. Wash stated he would not pre-judge the December decision and the FOMC will cut meeting frequency starting next year.
I. Market Outlook
Core Events:
- Fed holds rates steady, Wash declines to pre-judge December outcome: The FOMC left the federal funds rate at 3.75%-4.00%. Wash noted the number of policy meetings will be reduced from next year, he will not pre-commit to December’s move, and AI investment is also sensitive to interest rates.
→ 10-year US Treasury yield +2.08 bps to 5.0175%; 2-year yield -3.95 bps to 4.6975%; US Dollar Index -0.11% at 102.211.
Exclusive Viewpoint:
Reducing the frequency of FOMC meetings marks a notable shift in the Fed’s communication framework. Refusing to pre-judge December keeps policy uncertainty alive. The remark that AI capex is rate-sensitive directly ties AI spending cycles to monetary policy.
II. Overnight Market Action
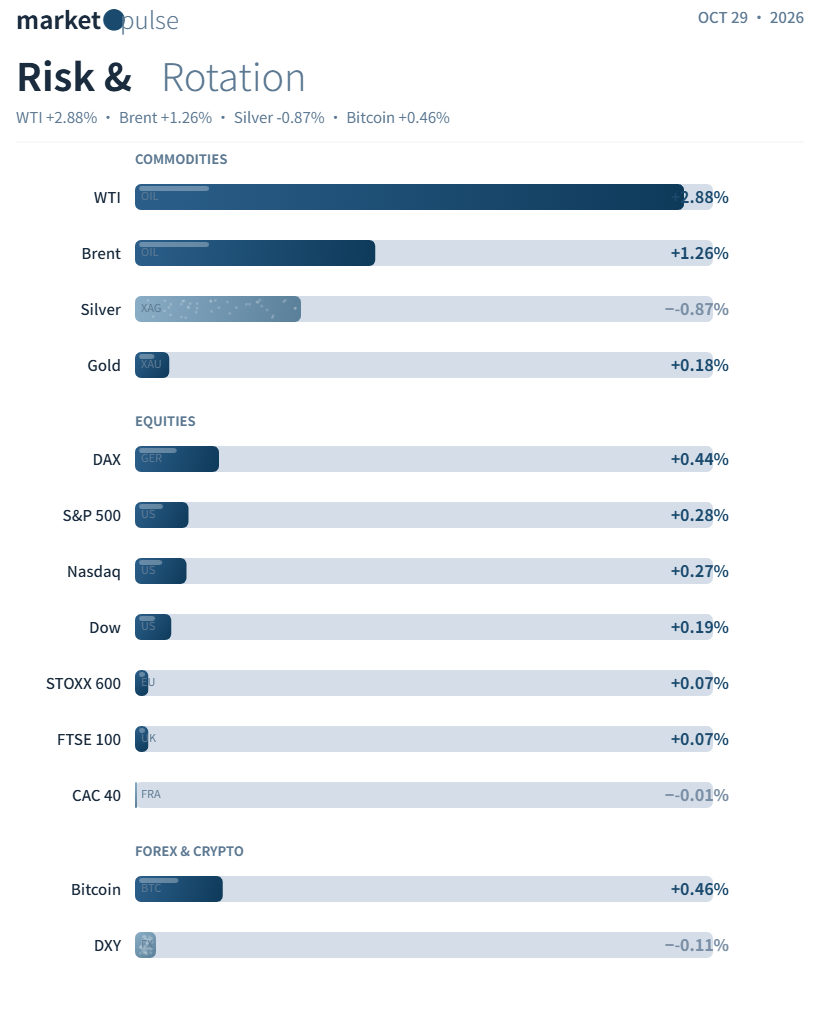
US Equities: Dow Jones +0.19% at 52475.10; S&P 500 +0.28% at 7743.98; Nasdaq +0.27% at 26549.85.
European Equities: STOXX 600 +0.07% at 644.14; DAX +0.44% at 25704.02; CAC 40 -0.01% at 7886.96; FTSE 100 +0.07% at 10694.50.
Rates: 10-year US Treasury yield +2.08 bps to 5.0175%; 2-year yield -3.95 bps to 4.6975%.
Commodities: WTI Dec contract +2.88% at $102.78/bbl; Brent +1.26% at $115.32/bbl. COMEX Gold +0.16% at $4081.20/oz; Silver -0.87% at $54.04/oz. Spot Gold +0.18% at $4067.46/oz.
FX: US Dollar Index -0.11% at 102.211.
Crypto: Bitcoin +0.46% at $81172.65.
III. Macro Headlines
1. 🏛️ Fed holds rates steady, Wash will not pre-judge December decision: Wash confirmed fewer FOMC meetings next year, declined to signal the December path, and said AI investment responds to borrowing costs.
Insight: Fewer meetings is a major adjustment to Fed communications. Keeping December open-ended sustains policy uncertainty. Linking AI capex to rates connects tech capital spending directly to monetary policy.
2. 🇨🇦 Bank of Canada hikes 25 bps to 2.5%, first increase in more than three years: The global tightening cycle remains ongoing.
IV. Corporate News
1. ☁️ Microsoft Azure revenue beats expectations with 48% growth, capex not spiraling out of control: Management guided Q2 capex above $50 billion and total revenue of $96bn–$97.1bn; shares surged in after-hours trading. AI spending is shifting from cost fears toward revenue delivery.
2. 📉 Google Q3 results miss estimates, free cash flow drops sharply and capex falls short of forecasts: Doubts over returns on AI investment deepen, creating a sharp contrast with Microsoft.
3. 💾 SK Hynix Q3 operating profit surged sevenfold year-over-year to 83.33 trillion won, announcing roughly 100 trillion won in shareholder returns. The firm expects memory shortages to persist through 2030, supporting the AI strategic value of memory chips.
4. 📈 Oracle jumped 13% in a single session: It forecasts positive free cash flow in the second half of FY28 and lower capex in FY29.
V. Key Events To Watch
· 📊 US Q3 real GDP, September personal income, PCE spending and core PCE inflation: Core PCE is the Fed’s preferred inflation gauge; the print will shape December hike odds after the October hold.
· 📊 US initial jobless claims: A test of labour market resilience.
· 🏛️ ECB rate decision and Lagarde press conference: Markets watch the ECB stance after the Bank of Canada’s surprise hike.
· 📊 Earnings from Samsung Electronics, Amazon and Intel: Critical guidance for AI hardware and cloud businesses.