I. Quick Snap
- Diplomatic signals pointing toward US-Iran negotiations hammered crude prices. WTI fell 4.38% to USD 86.85 per barrel, while Brent dropped 5.85% to USD 92.57 per barrel.
- The Jensen Huang controversy failed to derail a rebound in AI trade. The S&P 500 rose 2.35% to 7549.94, its strongest single-day advance since April 8. The Nasdaq gained 2.74%, marking its biggest rally since July 30.
II. Market Outlook
Key Catalysts
- US-Iran peace talk signals send crude sharply lower. WTI settled at USD 86.85, down 4.38%, and Brent closed at USD 92.57, falling 5.85%. Spot gold climbed 1.61% to USD 4136.20 an ounce, and silver advanced 2.88% to USD 53.4042 an ounce.
Exclusive View
The twin market narratives converged around expectations of easing inflation pressure: lower crude reduces upside risks to consumer prices and gives the Fed more policy room, while AI names bounced hard after a technical bear market. Even so, the ongoing board investigation into Nvidia’s governance remains a latent risk. If the scandal continues to gather steam, it could erode sentiment across the broader AI complex.
III. Overnight Markets
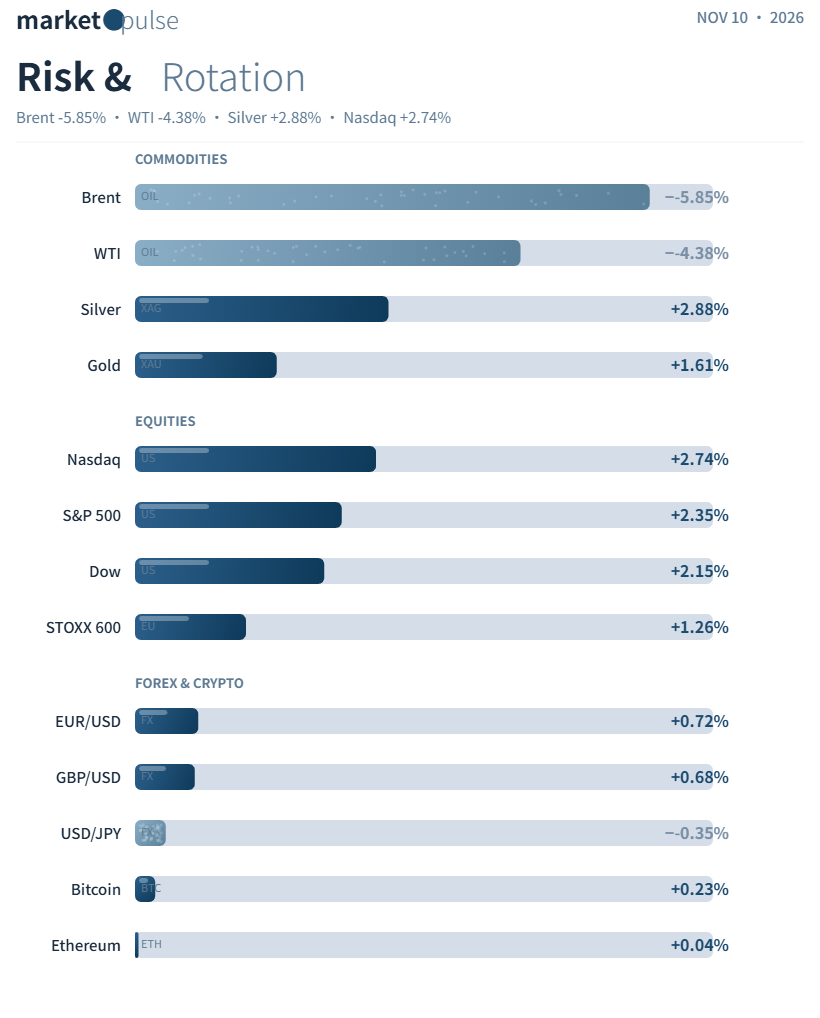
- US Equities: Dow Jones +2.15% to 52389.75. S&P 500 +2.35% to 7549.94, largest single-day gain since April 8. Nasdaq +2.74% to 25253.14, strongest session since July 30.
- European Equities: STOXX Europe 600 +1.26% to 656.52.
- Fixed Income: Two-year Treasury yield up 3.95 bps to 4.562%. Ten-year yield rose 1.48 bps to 4.874%.
- Commodities: WTI December crude -4.38% to 86.85. Brent -5.85% to 92.57. Spot gold +1.61% to 4136.20. Silver +2.88% to 53.4042.
- FX: EUR/USD +0.72% to 1.1223. USD/JPY -0.35% to 157.90. GBP/USD +0.68% to 1.3440.
- Crypto: Bitcoin +0.23% to 74928. Ethereum +0.04% to 2126.
IV. Macro Headlines
- New York Fed survey shows the share of respondents expecting higher unemployment one year ahead has climbed to the highest level since April 2020. Even as participants grow more downbeat on labour-market prospects, they see inflation staying steady. The split leaves the Fed room to take a patient stance on inflation.
- Trump’s approval rating lingers near the lows of his political career, with roughly 32% of Americans approving his performance, just above the record low of 31% hit in mid-October.
- The US Strategic Petroleum Reserve fell to 279.5 million barrels, its lowest level since October 1982. OPEC crude output rose in October, recovering to roughly 90% of its February levels. The SPR leaves far less energy security buffer, while returning OPEC supply partially offsets geopolitical risks.
V. Corporate News
- The investigation surrounding Jensen Huang widens, with the Nvidia board examining whether he became a target for foreign intelligence operations. Ties to Trump have drawn scrutiny, and governance risks may weigh on AI sentiment if headlines persist.
- Anthropic’s IPO roadshow could kick off as early as Tuesday. The offering will test investor valuation tolerance for leading AI stocks after the brutal tech sell-off.
- Musk’s Terafab targets monthly output of 700,000 storage wafers, a run-rate approaching Samsung’s total DRAM capacity. The aggressive expansion signals Tesla’s far larger ambitions inside chip manufacturing.
- US Democrats are preparing to launch investigations targeting Musk and other major tech figures, spreading political risk across big tech.
VI. Key Events to Watch
- US October CPI. With crude sliding and labour markets firm, the print will directly reset pricing for a December Fed hike.
- Speeches from Fed Governor Waller, Dallas Fed President Logan and Kansas City Fed President Schmid. Remarks will calibrate market expectations for the December policy meeting.
- Summary of opinions from the Bank of Japan’s October monetary policy meeting.
- EIA’s monthly Short-Term Energy Outlook. Forecasts on supply and demand carry extra weight with the SPR sitting at multi-decade lows.