Quick Snap
- US nonfarm payrolls rose by 165,000 in October, well above the 65,000 consensus forecast. The jobless rate fell to 4.1%, reviving bets that the Federal Reserve will raise rates in December.
- The S&P 500 closed the week down 2.7%, its worst weekly performance in more than a year. Crude posted a brutal weekly drop, with WTI falling 12.76% and Brent down 13.32%.
Market Outlook
Key Catalysts
- US payrolls smash estimates: The stronger-than-expected reading shows the labour market regaining traction after a mid-year slowdown and gives the Fed solid grounds to tighten policy again in December. The 10-year Treasury yield climbed 2.2 bps to 4.859%, the two-year yield rose 4.7 bps to 4.524%, and the US Dollar Index jumped 0.77% to 102.26.
- Oil plummets more than 12% weekly: WTI settled Friday at USD 90.83 per barrel, up 0.34% on the day, while Brent edged 0.03% higher to USD 98.32. Even with the modest Friday rebound, the week’s sell-off erased a large chunk of recent geopolitical risk premiums. The S&P 500 gained 0.32% to 7376.86, the Nasdaq added 264 points to 24579.43, and the Dow Jones slipped 0.46% to 51285.73.
Exclusive View
The blockbuster payroll print aligns with Williams’ recent remarks on the economy’s surprising resilience, stable labour markets and stubbornly high inflation, laying the data foundation for a December rate hike. Still, the S&P’s steep weekly decline signals markets are grappling with dual pressure: the higher-for-longer rates narrative and a sweeping re-rating across AI names.
Overnight Markets
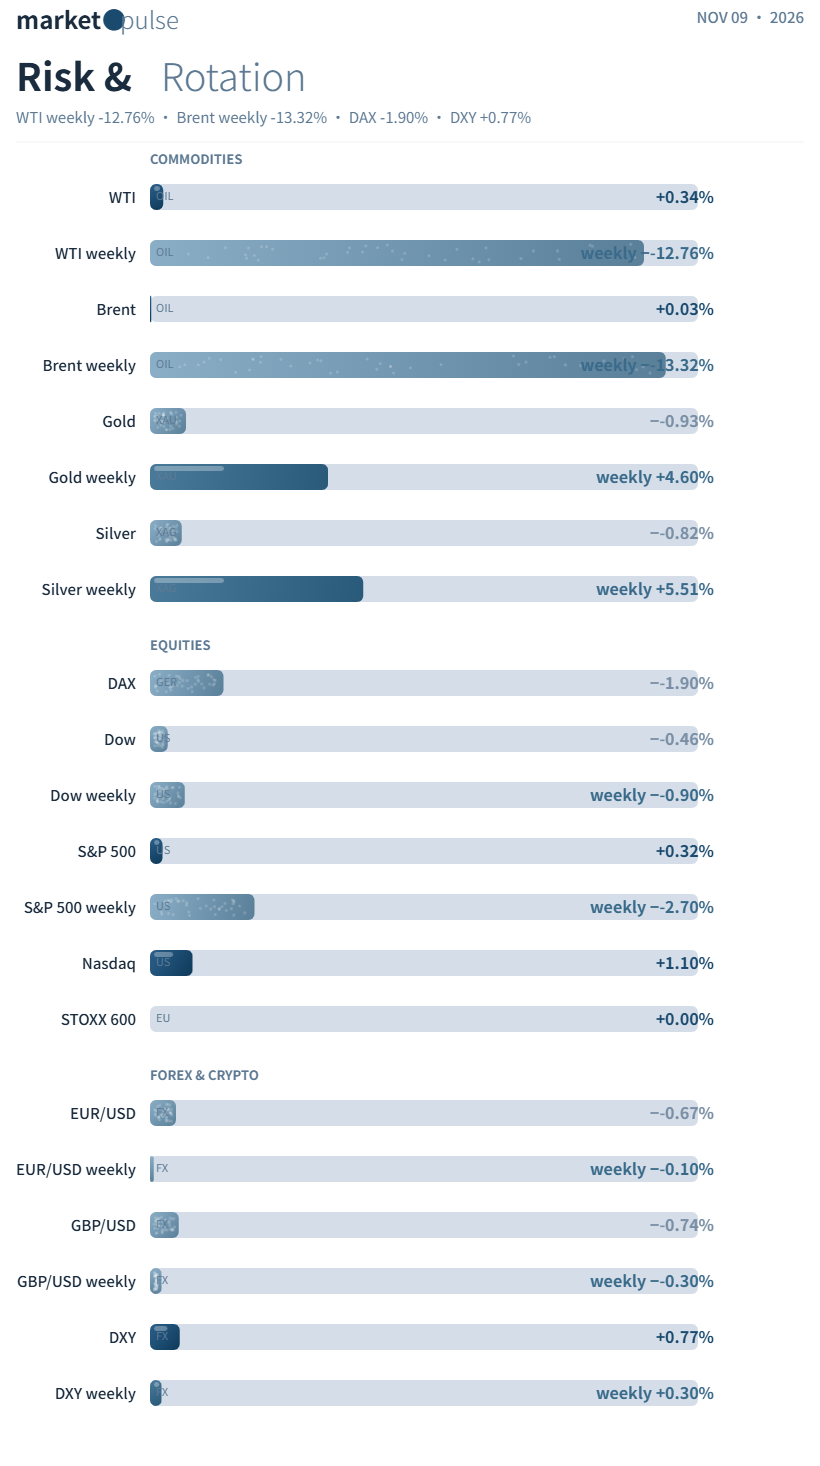
US Equities: S&P 500 +0.32% at 7376.86, weekly loss 2.7%. Nasdaq at 24579.43. Dow Jones -0.46% at 51285.73, down 0.9% week-to-date.
European Equities: STOXX 600 settled at 648.33; Germany’s DAX dropped 1.9%.
Fixed Income: 10-year US Treasury yield +2.2 bps to 4.859%. 30-year yield ticked up 1 bp to 5.262%. Two-year yield rose 4.7 bps to 4.524%, marking its sixth straight weekly fall.
Commodities: WTI crude +0.34% to 90.83, weekly -12.76%. Brent +0.03% to 98.32, weekly -13.32%. COMEX gold -0.93% to 4064.5, up 4.6% on the week. Silver -0.82% to 51.803, weekly gain 5.51%.
FX: DXY surged 0.77% to 102.26, up 0.3% for the week. EUR/USD fell 0.67% to 1.1143 for its sharpest single-day drop since October 1. GBP/USD lost 0.74% to 1.3355, the steepest decline since September 23.
Macro Headlines
1. US October payrolls surge past forecast. Unemployment drops to 4.1%, boosting market pricing for a December Fed hike. The data offers firm backing for tighter policy while inflation remains above target. Williams has repeatedly stressed inflation must return to the 2% objective.
2. Trump says the odds of striking Iran fall sharply if negotiation makes progress. His comments were the primary driver behind oil’s dramatic weekly pullback, as geopolitical risk premium unwound faster than traders anticipated.
3. Williams maintains a hawkish stance, highlighting robust growth, steady employment and persistent inflation that requires policy restraint.
4. Ueda notes underlying inflation is hovering near the 2% target, though upside risks remain, keeping the door open for further Bank of Japan tightening.
Corporate News
1. Tesla plans to phase out Cybertruck production by mid-next year, redirecting manufacturing capacity toward Cybercab and Optimus. The move represents a strategic reallocation toward autonomous driving and humanoid robots.
2. Anthropic’s expected valuation for its IPO has been cut to a range between USD 1.2 trillion and 1.3 trillion. Some investors question whether the roadshow can kick off in the week starting November 9, as the IPO window for leading AI firms narrows.
3. Berkshire Hathaway posted a 28% drop in Q3 net profit, with investment income nearly halved. Share buybacks hit a fresh high for the year, while its cash pile swelled to USD 377.4 billion, signalling a defensive posture.
Key Events to Watch
G7 Foreign Ministers’ meeting in Paris, running October 9–10. Investors will watch for coordinated stances on the Middle East and Ukraine amid ongoing US-Iran diplomatic talks.